Author: Rio

  • Debt Management Plan Affects Credit Score: 20 Best Facts

    Debt Management Plan Affects Credit Score: 20 Best Facts


    A debt management plan (DMP) is a structured programme designed to help individuals pay off unsecured debts, usually with the assistance of a credit counselling agency. Understanding how a DMP affects your credit score is essential for anyone considering this route, as it has both short-term and long-term implications. By exploring these 20 best facts, readers can make informed decisions about managing debt responsibly while minimising negative credit consequences.


    Debt Management Plan Affects Credit Score


    Debt Management Plan Affects Credit Score: 20 Best Facts


    How a DMP Works


    A debt management plan works by negotiating with creditors to reduce interest rates, waive late fees, and establish a single monthly payment. Credit counsellors guide individuals through this process, ensuring payments are made on time and distributed to creditors efficiently. This system can prevent accounts from going into collections, but it is important to recognise that the programme may also be reported on your credit report, impacting your score differently depending on your financial history.


    Who Should Consider a DMP


    Individuals who should consider a DMP are typically those struggling with high-interest credit cards or multiple debts they cannot manage. By consolidating payments and gaining professional guidance, participants can take control of their finances and reduce stress. However, some misconceptions exist, such as the belief that a DMP immediately fixes credit or guarantees score improvement. In reality, careful adherence and patience are required to see long-term positive effects.


    Initial Impact on Credit Score


    When starting a DMP, there may be an initial drop in your credit score. This happens because accounts enrolled in a plan might be reported as “managed by credit counsellor” or have changed terms. While this temporary dip can be discouraging, it is outweighed by the benefits of preventing defaults, collections, or bankruptcy. Understanding this short-term effect helps individuals stay committed to the programme and avoid making hasty financial decisions.


    Effect During Repayment Period


    During the repayment period, maintaining on-time payments is crucial for credit improvement. A DMP shows lenders that you are actively managing debt responsibly, which over time can rebuild your creditworthiness. Late or missed payments can worsen the impact, so following the payment schedule exactly as outlined by your credit counsellor is essential. Keeping communication open with creditors ensures the plan runs smoothly and avoids misunderstandings that could harm your score.


    How Long the Impact Lasts


    It is important to know how long a DMP may affect your credit score. While some negative marks may remain for a few months, consistent repayment generally leads to gradual improvement over time. Comparatively, a DMP is less damaging than declaring bankruptcy or allowing debts to go into collections. Understanding the timeline helps individuals set realistic expectations and plan their finances strategically, ensuring long-term credit recovery and stability.


    DMP vs Other Debt Solutions


    Compared to debt consolidation loans or credit counselling alone, a DMP offers a structured approach that combines guidance and negotiation with creditors. Unlike other methods, it ensures all payments are centralised and reduces the risk of missed obligations. By carefully choosing a certified credit counselling agency, participants gain access to resources and expertise that maximise the chance of successful debt repayment while minimising adverse effects on their credit report.


    Stopping Collection Calls and Reducing Stress


    One of the most significant benefits of a DMP is stopping collection calls and reducing financial stress. By consolidating debt payments into a single plan, individuals avoid the anxiety of juggling multiple creditors and late fees. This sense of control can positively influence financial decisions and help participants maintain discipline. Over time, this structured approach also reflects responsible debt management on credit reports, which can enhance trustworthiness in the eyes of future lenders.


    Regaining Financial Control


    Participating in a DMP also helps individuals regain financial control and develop better money management habits. By following a budget, tracking payments, and communicating with counsellors, participants learn skills that can prevent future debt issues. The plan can be particularly effective for those seeking long-term stability, as it encourages accountability and a gradual rebuilding of financial confidence, ultimately contributing to a stronger credit profile and more responsible financial behaviour.


    Long-Term Credit Improvement


    If managed properly, a DMP can improve credit scores over time. Regular, on-time payments show lenders a commitment to repaying debt, which can offset the initial negative impact of the programme. While results vary based on individual credit history, many participants see their scores begin to recover within months. This gradual improvement reinforces the importance of consistency and adherence to the plan, making it a practical solution for those aiming for long-term financial health.


    Responsible Debt Management Demonstrated

    A DMP demonstrates responsible debt management to future lenders and financial institutions. By showing consistent payment history and a clear plan for debt repayment, it can increase credibility and trustworthiness. Even though some accounts may be noted as part of a managed plan, this transparency often benefits individuals in the long term by signalling financial responsibility and a commitment to improving personal credit. Understanding this impact is essential for those navigating financial recovery.


    Temporary Score Drop is Normal

    When you enrol in a debt management plan, it’s normal for your credit score to drop temporarily. Accounts may show changes, such as “managed by credit counsellor”, which can concern some individuals. However, this short-term decline is often outweighed by the long-term benefits of avoiding defaults, collections, or bankruptcy. Knowing this helps participants stay committed, maintain consistent payments, and understand that the DMP is a tool for rebuilding credit responsibly rather than a quick fix.


    Accounts May Be Closed by Creditors

    Some creditors may close accounts once they are enrolled in a DMP. This can affect your available credit and temporarily impact your credit utilisation ratio. While this may slightly lower your credit score at first, it does not prevent long-term recovery. Participants should monitor their reports carefully, understand which accounts remain open, and focus on making all payments on time, ensuring that these changes ultimately support the goal of improved credit health over time.


    Limitations on New Credit

    While enrolled in a DMP, access to new credit may be limited. Lenders may view you as having actively managed debt, which could affect approvals for new loans or credit cards. However, this limitation encourages responsible debt management and ensures focus remains on paying off existing obligations. Over time, once the DMP is completed and payment history reflects consistency, individuals often regain access to credit with a stronger financial foundation and improved score.


    Making Consistent On-Time Payments

    One of the most important ways to minimise credit damage during a DMP is to make payments consistently and on time. Regular, timely payments show lenders a commitment to financial responsibility and contribute to gradual credit improvement. Even small delays can reduce the positive impact, so participants must prioritise DMP payments above discretionary spending. Over time, these consistent payments can rebuild credit and demonstrate reliability to future lenders, creating a foundation for long-term financial stability.


    Monitoring Your Credit Report

    Keeping track of your credit report while on a DMP is critical. Regular monitoring helps identify errors, ensures payments are reported correctly, and allows participants to track progress. By actively reviewing reports from major credit bureaus, individuals can detect any issues quickly, address discrepancies with creditors, and maintain an accurate record of financial behaviour. This proactive approach is essential for maximising the benefits of a DMP and gradually restoring a healthy credit score.


    Showing Responsible Debt Management to Lenders

    A DMP demonstrates to future lenders that you are committed to paying off debt responsibly. Even if some accounts are flagged as part of a managed plan, lenders often view this positively compared to ignored or defaulted accounts. Over time, this responsible behaviour helps build credibility, signalling that you are capable of managing financial obligations. Participants who maintain consistent payment history and clear communication with creditors often see improved trust and better lending opportunities in the future.


    Preventing Bankruptcy Through a DMP

    One of the biggest benefits of a debt management plan is its ability to help avoid bankruptcy. While bankruptcy severely damages credit for years, a DMP provides a structured path to repayment that mitigates long-term negative impacts. By following the plan, making on-time payments, and negotiating reduced interest rates, individuals can resolve debts more sustainably. Avoiding bankruptcy not only preserves future credit options but also enhances overall financial stability and long-term planning.


    Gradual Credit Score Recovery

    Credit improvement through a DMP is gradual, but consistent payment history and responsible management help restore scores over time. While the initial enrolment may lower credit temporarily, continued adherence leads to noticeable recovery within months. Individuals should focus on the long-term picture, understanding that consistent on-time payments and maintained communication with creditors gradually rebuild creditworthiness. This slow but steady approach often results in a healthier financial profile and stronger relationships with lenders.


    Debt Management Plan Affects Credit Score


    Learning Better Financial Habits

    A debt management plan teaches essential financial habits that prevent future debt problems. Participants learn budgeting, prioritising payments, and managing spending. These skills are valuable for long-term financial health, even after the DMP ends. By combining structured repayment with education, the plan fosters financial literacy, discipline, and confidence. Over time, these habits not only improve credit scores but also contribute to smarter money management, helping participants avoid recurring financial pitfalls and strengthen their overall financial security.


    Final Recap: The 20 Best Facts

    In summary, a debt management plan affects your credit score in multiple ways, with both short-term and long-term impacts. While initial dips, account closures, and limited credit access may occur, consistent payments, monitored progress, and responsible management lead to gradual improvement. Participants gain control of their finances, learn better habits, stop collection calls, and may avoid bankruptcy. Following a DMP strategically ensures long-term credit recovery, financial stability, and the development of habits that support a trustworthy financial profile.


    FAQs:


    1. How does a debt management plan affect credit score in the short term?

    A debt management plan affects credit score in the short term because creditors may note that your accounts are being managed through a credit counseling agency. While this notation itself is not negative, some lenders may view it cautiously. Additionally, if credit card accounts are closed as part of the plan, your credit utilization ratio may increase temporarily, which can cause a small dip in your credit score during the early stages.


    2. Does a debt management plan affect credit score negatively or positively?

    A debt management plan affects credit score both negatively and positively, depending on the timeline. Initially, scores may decline slightly due to account closures or changes in credit utilization. However, over time, a debt management plan affects credit score positively by promoting consistent on-time payments, reducing outstanding balances, and lowering overall debt. These improvements strengthen payment history and utilization, which are two major credit scoring factors.


    3. How long does a debt management plan affect credit score?

    A debt management plan affects credit score throughout the duration of the program, which typically lasts three to five years. The strongest impact is usually felt in the first few months. As balances decrease and payments remain on time, the negative effect lessens. Once the plan is completed, a debt management plan affects credit score less significantly, and many people see gradual improvement as financial stability increases.


    4. Can a debt management plan affect credit score less than debt settlement?

    Yes, a debt management plan affects credit score far less than debt settlement. Debt settlement often involves missed payments and accounts going into default, which seriously damage credit scores. In contrast, a debt management plan affects credit score more mildly because you continue making regular payments, avoid charge-offs, and maintain a positive payment history. This makes debt management a safer option for protecting long-term credit health.


    5. Will a debt management plan affect credit score after completion?

    After completion, a debt management plan affects credit score in a positive way for many individuals. By the end of the plan, debts are significantly reduced or eliminated, and payment history is stronger. Although closed accounts may remain on your report, lenders often focus more on current behavior. As long as you continue using credit responsibly, a debt management plan affects credit score favorably over time.


    6. Does a debt management plan affect credit score differently for credit cards?

    A debt management plan affects credit score mainly through credit card accounts because they play a major role in utilization ratios. Credit card accounts are often closed to prevent further borrowing, which can temporarily raise utilization. However, as balances are paid down steadily, utilization improves. Over time, a debt management plan affects credit score positively by lowering revolving debt, which is a key factor in credit scoring models.


    7. How fast can a debt management plan affect credit score improvement?

    A debt management plan affects credit score improvement gradually, not instantly. Most people begin to see stabilization within three to six months and noticeable improvement within six to twelve months. This depends on payment consistency and how quickly balances decline. While early changes may be modest, a debt management plan affects credit score improvement more clearly as debt levels drop and financial habits become more stable.


    8. Does a debt management plan affect credit score when accounts are closed?

    A debt management plan affects credit score when accounts are closed because it can shorten average account age and increase utilization temporarily. These factors may cause a slight drop at first. However, closed accounts in good standing remain on your credit report for years. As balances are reduced, the long-term impact improves, and a debt management plan affects credit score more positively over time.


    9. Can a debt management plan affect credit score more than late payments?

    No, a debt management plan affects credit score far less than repeated late payments. Late payments can stay on your credit report for up to seven years and significantly lower your score. A debt management plan helps prevent missed payments by organizing debt into one structured plan. As a result, a debt management plan affects credit score more gently while supporting long-term credit recovery.


    10. Is a debt management plan worth it if it affects credit score?

    Even though a debt management plan affects credit score initially, it is often worth it for people struggling with high-interest debt. The plan provides structure, lower interest rates, and predictable payments. Over time, reduced debt and consistent payment history outweigh short-term score changes. For many, a debt management plan affects credit score in a way that supports long-term financial health and stability.


  • Car Insurance Quote: 20 Best Trusted Ways to Save Big

    Car Insurance Quote: 20 Best Trusted Ways to Save Big

    Getting the right car insurance quote is one of the smartest financial decisions a vehicle owner can make. A few minutes spent comparing quotes can save hundreds of dollars every year while ensuring your coverage remains reliable and legally compliant. Many drivers overpay simply because they don’t review their options regularly. With the right strategy, you can lower your premium while still enjoying peace of mind and strong protection.


    Car Insurance Quote: 20 Best Trusted Ways to Save Big

    Why Getting the Right Car Insurance Quote Matters

    A car insurance quote determines how much you will pay to protect yourself, your vehicle, and others on the road. Choosing the wrong quote may result in either overpaying or being underinsured during an accident. A good quote balances affordability with proper coverage. When you compare quotes carefully, you gain control over your finances and avoid unpleasant surprises when filing a claim.


    What Is a Car Insurance Quote and How It Works

    A car insurance quote is an estimate of what an insurer will charge based on your personal profile and coverage needs. Companies calculate quotes using factors such as your age, driving record, car model, and location. Since each insurer uses its own formula, the same driver can receive widely different prices from different companies for similar coverage levels.


    Key Factors That Affect Your Car Insurance Quote


    Several factors influence your final premium, including your driving history, credit score, type of vehicle, and even your ZIP code. Drivers in high-traffic or accident-prone areas usually pay more. Likewise, sports cars cost more to insure than family sedans. Understanding these elements allows you to make informed choices that directly lower your insurance costs.


    Types of Car Insurance Quotes You Can Get


    There are multiple types of car insurance quotes depending on your needs. These include liability-only, full coverage, comprehensive, collision, non-owner, SR22, and classic car insurance quotes. Each type serves a different purpose, and selecting the right one ensures you are protected without paying for coverage you don’t truly need.


    20 Best Trusted Ways to Save Big on Car Insurance Quotes


    Saving on car insurance doesn’t require sacrificing coverage. With smart planning and awareness, you can significantly reduce your premium while remaining well protected.


    1. Compare Multiple Quotes Online

    Always compare at least three insurers before choosing one because prices and coverage can vary widely between companies. Online comparison tools make this process fast and transparent, allowing you to review premiums, coverage limits, and customer ratings side by side. This approach helps you spot hidden fees, avoid overpriced policies, and confidently select the best-value option for your needs.


    2. Choose the Right Coverage, Not Just the Cheapest

    The cheapest policy may look attractive, but it often leaves you financially exposed in real accident situations. Always match coverage limits to your actual risk level and financial capacity instead of focusing only on the lowest price. A balanced policy protects your savings and ensures you are not burdened with unexpected expenses later.


    3. Increase Deductibles Smartly

    Although it should be done carefully, increasing your deductible can drastically lower your monthly rate. In the event of an accident or damage, pick a deductible amount that you can afford. The goal of saving money on insurance is defeated if your deductible is too high because you can have financial difficulties when filing claims.


    4. Bundle Insurance Policies

    Combining your auto insurance with home or renters insurance often leads to valuable multi-policy discounts. Insurers reward customers who bring more than one policy because it reduces administrative costs. Bundling also simplifies management by letting you deal with one provider, one payment schedule, and often better overall customer support.


    5. Maintain a Clean Driving Record

    A clean driving record is one of the most powerful ways to keep your insurance premiums low. Avoiding accidents, speeding tickets, and traffic violations shows insurers that you are a low-risk driver. Over time, this responsible behavior can qualify you for safe-driver discounts and better renewal quotes.


    6. Improve Your Credit Score

    Many insurers use credit-based insurance scores to determine premiums. A higher credit score signals financial responsibility and reliability, which insurers reward with lower rates. Paying bills on time, reducing debt, and monitoring your credit report regularly can help improve your score and directly lower your insurance costs.


    7. Choose Usage-Based Insurance

    Usage-based or pay-as-you-drive insurance tracks how and how much you drive using telematics devices or mobile apps. If you drive fewer miles or follow safe driving habits, you can earn significant discounts. This option is especially beneficial for remote workers, retirees, or people who rarely use their vehicles.


    8. Ask for All Available Discounts

    Many drivers miss out on savings simply because they don’t ask about discounts. Insurers often offer special reductions for students, military personnel, seniors, safe drivers, and even for paperless billing. Always request a full list of discounts and confirm that all applicable ones are applied to your policy.


    9. Choose the Right Car Model

    The type of vehicle you drive plays a major role in determining your insurance premium. Cars with high safety ratings, lower repair costs, and fewer theft records are cheaper to insure. Before buying a vehicle, check its insurance cost to avoid unexpected premium increases after purchase.


    10. Avoid Frequent Small Claims

    While insurance is meant to protect you, filing too many small claims can raise your future premiums. Insurers may view you as a higher-risk customer. For minor damages, consider paying out of pocket if financially possible, preserving your claim-free record and keeping long-term insurance costs lower.


    11. Review Your Policy Annually

    Your insurance needs change over time due to factors like relocation, vehicle age, or lifestyle changes. Reviewing your policy annually helps ensure you’re not overpaying for unnecessary coverage or missing better deals elsewhere. Regular reviews also allow you to adjust coverage based on your current financial and personal situation.


    12. Install Safety Devices

    Installing safety and anti-theft devices such as alarms, GPS trackers, and immobilizers reduces the risk of theft and accidents. Many insurers reward this added protection with premium discounts. These devices not only save money on insurance but also provide peace of mind and better vehicle security overall.


    13. Remove Unnecessary Coverage

    As your car ages, certain coverage types like comprehensive or collision may no longer be cost-effective. If the repair cost exceeds the car’s value, maintaining such coverage may not make financial sense. Reviewing and removing unnecessary coverage can significantly reduce your insurance premium without increasing your risk.


    14. Pay Annually Instead of Monthly

    Paying your insurance premium annually instead of monthly often helps avoid installment fees and interest charges. Many insurers offer small discounts for full upfront payments. If your budget allows, this option reduces overall cost and simplifies payment management by eliminating frequent billing cycles.


    15. Compare Local and National Insurers

    While large national insurers offer wide coverage, local or regional companies sometimes provide better personalized service and competitive pricing. Comparing both options ensures you don’t miss out on affordable policies that suit your specific location and driving profile. Always check reviews and claim settlement records before deciding.


    16. Try Pay-Per-Mile Insurance

    Pay-per-mile insurance is ideal for drivers who use their vehicles infrequently. Instead of paying a flat premium, you pay based on the distance you actually drive. This model can significantly reduce costs for low-mileage drivers while still providing reliable coverage when the vehicle is on the road


    17. Update Quotes After Major Life Changes

    Major life changes such as marriage, moving to a safer neighborhood, or starting a new job can positively affect your insurance rate. Updating your insurer with this information ensures your premium reflects your current risk profile, often resulting in immediate or future cost reductions.


    18. Use Independent Insurance Agents

    Independent insurance agents work with multiple companies rather than just one. This allows them to compare policies across several insurers and find the best deal for your situation. Their expertise can save time and money while helping you understand policy terms more clearly.


    19. Avoid Coverage Lapses

    Allowing your insurance coverage to lapse, even for a short period, signals risk to insurers and often leads to higher premiums later. Maintaining continuous coverage shows reliability and helps you qualify for better rates. Always renew on time or arrange a new policy before the old one expires.


    20. Monitor Market Rate Trends

    Insurance prices change due to inflation, claim trends, and regulatory updates. Staying informed about these trends helps you know when it’s a good time to renegotiate or switch providers. Proactive monitoring ensures you always pay a fair and competitive price for your coverage.


    Best Online Tools to Get Car Insurance Quotes

    Trusted platforms such as Policygenius, NerdWallet, The Zebra, and official insurer websites provide transparent, regulated comparisons. These tools help you review coverage features, customer reviews, and pricing side by side, ensuring your final choice is both economical and reliable.


    Common Mistakes to Avoid When Getting a Car Insurance Quote

    Many drivers choose the cheapest quote without reviewing exclusions or policy limits. Others provide inaccurate information, leading to denied claims later. Skipping comparisons and ignoring policy fine print are also costly errors. Being honest and detail-oriented during the quote process protects you financially in the long run.


    How to Choose a Trustworthy Insurance Provider

    Always verify the insurer’s financial strength ratings, customer service reviews, claim settlement ratio, and regulatory approval. A slightly higher premium with a reliable company is far better than cheap coverage that fails when you need it most.


    Car Insurance Quotes for Special Situations

    Drivers such as seniors, military personnel, high-risk drivers, and classic car owners often need specialized policies. These quotes are tailored to unique risk profiles and may offer discounts or coverage benefits unavailable in standard policies.


    Final Thoughts: How to Lock the Best Car Insurance Quote Today

    The best car insurance quote is one that balances cost, coverage, and trust. By comparing options, staying informed, and reviewing your policy annually, you can protect both your vehicle and your finances effectively. Smart decisions today can save thousands over a lifetime of driving.


    FAQS


    1. What is Car Insurance and why is it important?
    Car Insurance is a financial agreement between you and an insurer that protects you from unexpected losses related to your vehicle. It helps cover repair costs, theft, accidents, and third-party liabilities. Having proper coverage ensures peace of mind, legal compliance, and financial security in case of emergencies on the road.


    2. How does Car Insurance work?
    Car Insurance works by charging a premium in exchange for coverage against specific risks mentioned in the policy. When an accident or damage occurs, you file a claim with the insurer, who then verifies the incident and compensates you based on the policy terms, deductibles, and coverage limits.


    3. What types of coverage are included in Car Insurance?
    Car Insurance usually includes third-party liability, own damage, personal accident cover, and optional add-ons like zero depreciation or roadside assistance. These components work together to provide protection against legal claims, vehicle damage, and personal injuries, ensuring complete safety for both driver and vehicle.


    4. Is Car Insurance mandatory by law?
    Yes, Car Insurance is legally required in most countries, at least for third-party liability coverage. This ensures that any damage or injury caused to others is financially compensated. Driving without insurance can lead to fines, legal trouble, and suspension of vehicle registration.


    5. How is Car Insurance premium calculated?
    Car Insurance premium depends on factors like vehicle age, model, engine size, location, claim history, and selected coverage. Cars with higher risk profiles attract higher premiums, while safe driving records and security features help in lowering overall insurance costs.


    6. What is a No Claim Bonus in Car Insurance?
    A No Claim Bonus in Car Insurance is a discount earned for not filing any claims during the policy period. It reduces the premium at renewal and increases progressively each claim-free year, encouraging careful driving while rewarding policyholders with long-term savings.


    7. Can Car Insurance be transferred to a new owner?
    Yes, Car Insurance can be transferred to the new owner when a vehicle is sold. The buyer must apply for the transfer within a specific timeframe to ensure that the policy remains valid and claims are not rejected due to ownership discrepancies.


    8. What documents are needed to buy Car Insurance?
    To purchase Car Insurance, you usually need the vehicle registration certificate, previous policy details, identity proof, address proof, and sometimes a vehicle inspection report. These documents help insurers verify ownership, vehicle condition, and policy eligibility.


    9. How can I reduce my Car Insurance premium?
    You can reduce your Car Insurance premium by choosing a higher deductible, avoiding unnecessary add-ons, maintaining a claim-free record, and installing anti-theft devices. Comparing policies online also helps in finding affordable and suitable coverage options.


    10. What is zero depreciation in Car Insurance?
    Zero depreciation in Car Insurance is an add-on that allows you to claim the full cost of repairs without accounting for depreciation on parts. This is especially useful for new cars, as it ensures higher claim amounts and reduces out-of-pocket expenses.


    11. Does Car Insurance cover natural disasters?
    Car Insurance usually covers natural disasters such as floods, earthquakes, cyclones, and storms under comprehensive policies. This ensures that vehicle damage caused by unpredictable environmental events is financially compensated without burdening the vehicle owner.


    12. What is not covered under Car Insurance?
    Car Insurance does not cover damages due to drunk driving, driving without a valid license, regular wear and tear, mechanical failure, or illegal modifications. Understanding exclusions is important to avoid claim rejection and financial disappointment during emergencies.


    13. How long does Car Insurance claim settlement take?
    Car Insurance claim settlement time depends on the insurer, type of claim, and documentation. Simple cashless claims may be settled within days, while reimbursement claims might take longer. Providing complete and accurate documents speeds up the process significantly.


    14. Can I renew Car Insurance after expiry?
    Yes, Car Insurance can usually be renewed after expiry, but delays may require vehicle inspection and may result in loss of No Claim Bonus. It is always recommended to renew before expiry to avoid coverage gaps and legal issues.


    15. What is a cashless claim in Car Insurance?
    A cashless claim in Car Insurance allows repairs to be done at network garages without paying upfront. The insurer directly settles the bill with the garage, making the process smooth, quick, and financially stress-free for the vehicle owner.


    16. Is Car Insurance valid across the country?
    Yes, Car Insurance is valid across the country in which it is issued, allowing you to drive freely across states or regions. This nationwide coverage ensures legal compliance and financial protection wherever your vehicle travels


    17. Can Car Insurance be customized?
    Car Insurance can be customized using add-ons such as engine protection, roadside assistance, key replacement, and zero depreciation. These optional covers allow you to tailor your policy according to your driving habits, location, and vehicle usage.


    18. What happens if I drive without Car Insurance?
    Driving without Car Insurance is illegal in most regions and can result in fines, penalties, or imprisonment depending on local laws. It also exposes you to huge financial risks if you cause damage to others or your own vehicle.


    19. Does Car Insurance cover theft?
    Car Insurance under a comprehensive policy covers vehicle theft and total loss. The insurer compensates based on the insured declared value after verification, helping owners recover financially from such unfortunate incidents.


    20. How do I choose the best Car Insurance policy?
    To choose the best Car Insurance policy, compare coverage, claim settlement ratio, customer reviews, add-on options, and premium rates. Selecting a reliable insurer with transparent terms ensures better service, smoother claims, and long-term satisfaction.


  • Car Insurance Refund Calculation: 20 Best Payout Estimates

    Car Insurance Refund Calculation: 20 Best Payout Estimates

    Car insurance refund calculation helps vehicle owners estimate the amount of premium they can get back when cancelling a policy before its expiry. Many policyholders are unaware that refunds are possible in cases such as vehicle sale, duplicate policies, or early termination. Understanding refund rules in advance ensures smoother processing, reduces confusion, and helps make better financial decisions.

    A car insurance refund calculator is an online tool that allows users to get an estimated payout instantly. By entering details like policy start date, cancellation date, and premium paid, users can see approximate refund amounts. This helps policyholders plan their finances and avoid surprises, providing clarity and transparency before initiating cancellation with the insurer.


    Car Insurance Refund Calculation: 20 Best Payout Estimates

    Car Insurance Refund Calculator


    The car insurance refund calculator takes inputs such as policy start date, end date, total premium paid, and cancellation date to generate an approximate refund amount. This online tool saves time, avoids errors, and gives users a clear understanding of what they can expect from their insurer before submitting a cancellation request.

    These calculators also account for policy type, any claims made, and remaining coverage period. While they provide estimates, actual refunds may vary depending on insurer rules, taxes, and administrative deductions. Using a calculator ensures realistic expectations and allows policyholders to make informed decisions about cancelling or switching policies.

    How Car Insurance Refund Calculation Works


    Refunds are generally calculated using the pro-rata or short-rate method. The pro-rata method refunds the unused premium proportionally, while the short-rate method deducts additional penalties for early cancellation. Understanding these methods helps policyholders anticipate the refund amount accurately and decide whether early cancellation is financially worthwhile.

    Insurers also deduct administrative fees, applicable taxes, and any claim-related adjustments. If a claim has been made, the refund may be reduced or denied. Knowing how the calculation works ensures that policyholders are prepared for potential deductions and can plan accordingly before cancelling the policy.

    20 Best Car Insurance Refund Payout Scenarios

    1. Cancelled Within the Free-Look Period


    Cancelling your policy within the free-look period, usually 14 days, often results in a near-full refund. Insurers deduct only minimal administrative charges. This option is ideal for policyholders who purchased coverage accidentally or found better insurance shortly after buying the policy.

    2. Policy Cancelled After One Month


    If you cancel after one month, the insurer deducts charges for the coverage already used and service fees. Refunds are lower than early cancellations due to short-rate penalties. Using a calculator before cancelling ensures you know the estimated payout and helps make informed decisions.

    3. Policy Cancelled After Three Months


    Cancelling after three months results in further reduced refunds because of short-rate deductions. Policyholders may receive only a partial amount. A refund calculator is useful to evaluate if cancellation is financially viable and prevents unexpected loss of premium.


    4. Policy Cancelled After Six Months


    After six months, most of the premium has already been applied. Refunds are minimal for comprehensive policies, and third-party policies rarely offer any refund at this stage. Knowing your eligibility before cancelling avoids financial disappointment.

    5. Policy Cancelled After Nine Months

    Late cancellations often result in negligible refunds. Insurers may deduct nearly the entire premium. Using a refund calculator helps determine whether cancelling at this point is worthwhile and provides clarity on expected payout.

    6. Car Sold During Policy Term

    When a vehicle is sold, the policy can be cancelled, and the remaining premium refunded. Proof of sale and ownership transfer documents are usually required by the insurer for processing the refund.

    7. Vehicle Ownership Transferred


    If the vehicle ownership is transferred, the policy can be either cancelled or transferred to the new owner. Cancelling the policy may result in a partial refund after deductions.


    8. Duplicate Policy Purchased


    If two policies are accidentally purchased for the same vehicle, insurers usually allow one policy to be cancelled with a refund for the unused portion. Verification is required before the refund is processed.

    9. Incorrect Policy Details


    Policies issued with incorrect information such as vehicle registration or owner details can be cancelled. Refunds are processed after verification and correction of the policy information by the insurer.

    10. Policy Cancelled Due to Non-Usage


    If a vehicle is unused for a period due to travel, mechanical issues, or other reasons, some insurers allow policy cancellation with a partial refund. Proof of non-usage may be required.

    11. Vehicle Stolen and Claim Settled


    After a vehicle theft claim is settled, the policy is automatically terminated. Refunds may apply for unused add-ons or remaining premium, depending on the insurer’s rules.

    12. Total Loss Settlement


    In total loss cases, the policy ends after claim settlement. Refund eligibility depends on the remaining premium and policy terms.

    13. Engine Damage Policy Cancellation


    Engine protection add-ons may be cancelled separately. Refunds are calculated based on the unused coverage period and whether any claims were filed under the add-on.

    14. Add-On Cover Cancellation


    Other add-ons, like roadside assistance or zero depreciation, can sometimes be cancelled independently, allowing partial refunds if unused.

    15. Long-Term Policy Cancellation


    Long-term insurance policies have stricter refund rules. Refunds are typically allowed only in cases like vehicle sale or total loss, and may be lower compared to short-term policy cancellations.

    16. Third-Party Policy Refund Rules


    Third-party policies usually have limited refund options once coverage has started. Refunds are mostly allowed only in special cases, such as vehicle transfer or early cancellation within the free-look period.

    17. Comprehensive Policy Refund Rules


    Comprehensive policies offer more flexibility for refunds, especially when cancelled early without claims. Refunds may include unused coverage and add-ons if applicable.

    18. Refund With Active Claim


    If a claim has been made, refunds are typically reduced or denied. The claim history has a major impact on refund eligibility and final payout amounts.

    19. Refund Without Any Claim


    Policies without any claims usually qualify for higher refunds. Early cancellation without claims maximizes the refund and ensures policyholders receive a fair portion of the unused premium.


    20. Online vs Offline Cancellation Refund


    Online cancellations are faster and more transparent, providing quicker refund processing. Offline cancellations can take longer due to manual paperwork, verification, and bank processing time.


    Factors That Affect Car Insurance Refund Amount


    Refund amounts depend on multiple factors including remaining policy duration, claims history, policy type, insurer rules, and applicable government taxes. Administrative charges and service fees also reduce final payout.

    Using a refund calculator before cancelling ensures policyholders have realistic expectations and helps them make informed financial decisions. Understanding these factors reduces surprises and delays during refund processing.


    Car Insurance Refund Calculation Example


    For example, if you paid $600 for a one-year policy and cancel after three months, short-rate deductions may apply. You might receive approximately $350 after fees and administrative charges.
    This highlights why refund amounts vary across insurers and policies. Always estimate the refund before cancelling your policy to avoid financial surprises.


    How Long Does a Car Insurance Refund Take?


    Refunds are generally processed within 7–15 working days after approval by the insurer. Bank processing may take a few extra days before funds reflect in your account.

    Delays can occur due to missing documents, verification issues, or high processing volumes. Submitting complete documentation speeds up the refund process significantly.


    Tips to Maximize Your Insurance Refund

    Cancel policies early to reduce short-rate deductions and maximize refunds. Avoid making unnecessary claims if planning to cancel soon, and ensure all documents are ready for smooth processing.

    Planning cancellations strategically helps policyholders receive higher refunds and saves time. Using an online calculator before cancellation provides clarity and helps avoid surprises.


    Final Thoughts


    Car insurance refund calculation allows policyholders to make informed decisions before cancelling coverage. Understanding scenarios, methods, and insurer rules improves financial outcomes.

    Using a car insurance refund calculator ensures accurate estimates of payouts, helping policyholders plan cancellations efficiently and avoid unpleasant surprises.

    FAQS


    1. What is a Car Insurance Refund Calculation?

    A Car Insurance Refund Calculation is the method used by insurance companies to determine how much money a policyholder can get back if they cancel their policy before it expires. It takes into account the premium already paid, the duration of coverage used, and any administrative fees to ensure the refund is accurate and fair.

    2. How is Car Insurance Refund Calculation Done?

    The Car Insurance Refund Calculation involves assessing the unused portion of the policy premium. Insurers deduct charges for the coverage already provided and sometimes administrative fees. The remaining amount is returned to the policyholder. It is always important to review your insurance terms, as each company may have slightly different rules for refund calculations.

    3. Can I Get a Full Refund on Car Insurance?

    A full refund is usually only possible if the policy is canceled immediately after purchase. The Car Insurance Refund Calculation generally reduces the amount based on how long the policy has been active. Administrative fees, taxes, and the coverage already used often reduce the refund, making early cancellation the most effective way to maximize returns.

    4. Does Car Insurance Refund Calculation Include Taxes?

    Yes, taxes are often included in the Car Insurance Refund Calculation. Some insurers may deduct applicable taxes or adjust the refundable amount according to local tax laws. This ensures that the policyholder receives the correct refund amount while complying with government regulations, making it essential to check the insurer’s specific tax treatment before canceling.

    5. How Long Does It Take to Receive a Refund?

    After initiating a cancellation, the Car Insurance Refund Calculation is performed by the insurer, which may take a few days to several weeks. The process involves verifying the policy, calculating the refund, and processing the payment. Submitting all required documents promptly can help speed up the timeline and ensure a smooth refund experience.

    6. Are There Fees Deducted During Car Insurance Refund Calculation?

    Yes, insurers often deduct administrative or processing fees during the Car Insurance Refund Calculation. These fees cover handling costs for cancellations and paperwork. Additionally, some insurers may include a small deduction for early termination of the policy, making it important to understand the fine print before requesting a refund.

    7. Can I Cancel My Car Insurance Anytime?

    Yes, most insurance companies allow policyholders to cancel anytime. The Car Insurance Refund Calculation determines how much money will be returned based on the unused coverage period and any fees. However, canceling early may lead to a higher refund, while canceling later will usually reduce the refundable amount.

    8. Is Car Insurance Refund Calculation Different for Comprehensive Policies?

    The Car Insurance Refund Calculation can vary depending on the type of policy. Comprehensive insurance often involves higher premiums, so the refund may be larger in absolute terms. However, the same principle applies: insurers deduct charges for coverage already used and administrative costs before returning the remaining balance to the policyholder.

    9. Do Insurers Refund Premiums Automatically?

    Refunds are usually not automatic. After requesting cancellation, insurers perform the Car Insurance Refund Calculation to determine the exact amount due. The policyholder may need to submit a formal request or required documents. Once verified, the insurer processes the refund, often via bank transfer or cheque.

    10. Can Refunds Be Claimed for Lapsed Policies?

    Generally, refunds are not available for lapsed policies. The Car Insurance Refund Calculation applies only when a policy is actively canceled before expiration. If the policy has already expired or lapsed due to non-payment, the premium is usually non-refundable, highlighting the importance of timely cancellations.

    11. How Do I Request a Car Insurance Refund?

    Get in touch with your insurance company and submit a cancellation request to get a refund. To calculate the refundable amount, the insurer will use the Car Insurance Refund Calculation. To prevent delays in processing your refund, make sure you supply all necessary information, including your policy number, identity, and proof of purchase.


    12. Does No Claim Bonus Affect Refunds?

    Yes, the No Claim Bonus (NCB) may affect the Car Insurance Refund Calculation. Some insurers adjust the refund based on accrued bonuses or policy discounts. While the unused premium is refundable, the NCB may reduce or increase the amount, depending on the insurer’s rules, making it crucial to confirm with your provider.

    13. Are Online Refunds Faster?

    Yes, requesting a refund online can speed up the Car Insurance Refund Calculation process. Many insurers have digital forms and automated systems to calculate the refund, reducing paperwork and manual processing time. Submitting accurate information online ensures a quicker and smoother refund experience.

    14. Can Refunds Be Transferred to Another Policy?

    Some insurers allow the refund amount from one policy to be adjusted toward a new policy. During the Car Insurance Refund Calculation, the insurer may offer to transfer the unused premium instead of issuing a cash refund. This can be convenient for those planning to switch policies without losing money.

    15. What Happens If I Stop Paying Premiums?

    Stopping payments without formally canceling may not trigger a Car Insurance Refund Calculation. In many cases, the policy may lapse, and no refund is provided. To ensure a refund, always submit a cancellation request and allow the insurer to calculate the refundable amount according to their terms.

    16. Can I Check Refund Amount Before Canceling?

    Yes, many insurers provide an estimated Car Insurance Refund Calculation before cancellation. You can request a quote for the refundable amount, allowing you to make an informed decision. This helps you understand deductions for administrative fees, taxes, and coverage already used.

    17. Does Refund Calculation Differ for Third-Party Policies?

    Yes, the Car Insurance Refund Calculation for third-party policies may differ from comprehensive ones. Since third-party policies usually have lower premiums, the refundable amount may be smaller, but the principle remains the same: deductions are made for the coverage already provided and any administrative fees
    .
    18. Is Car Insurance Refund Taxable Income?

    No, the refunded amount after a Car Insurance Refund Calculation is usually not considered taxable income. It is a return of your unused premium. However, always confirm local tax regulations to ensure compliance, especially if the refund is substantial.

    19. How Can I Maximize My Refund?

    To maximize your refund, cancel your policy early before most of the coverage period passes. The Car Insurance Refund Calculation reduces refunds based on the time already covered, so acting promptly ensures the highest possible return. Avoiding unnecessary fees also helps increase the refundable amount.

    20. What Documents Are Needed for Refund?

    Typically, you will need a copy of your policy, a formal cancellation request, proof of identity, and payment details for the refund. These documents are necessary for the insurer to perform the Car Insurance Refund Calculation accurately and ensure the refund is processed without delays.


  • Savings vs Investing: 20 Best Trusted Examples to Build Wealth Safely

    Savings vs Investing: 20 Best Trusted Examples to Build Wealth Safely

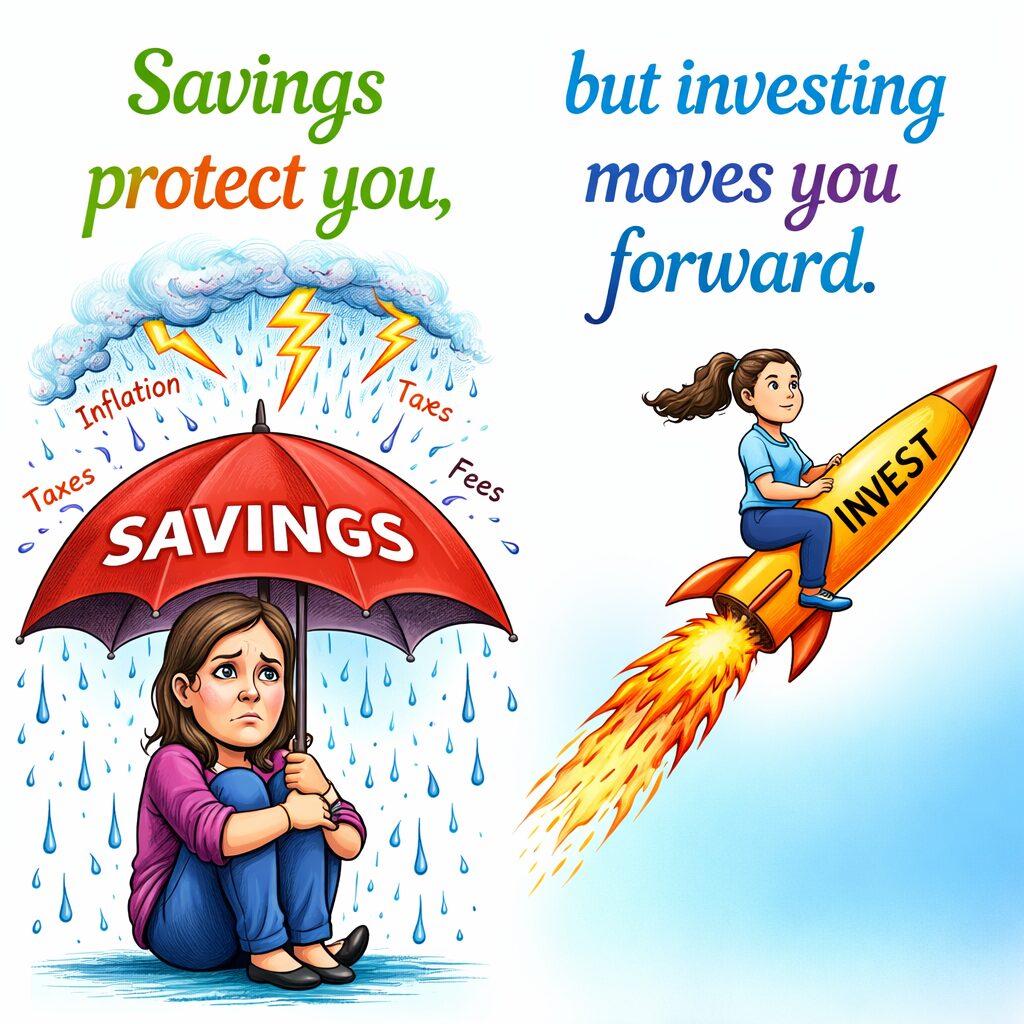
    Understanding the difference between savings and investing is the first step toward financial success. Savings protect your money and provide liquidity for emergencies or short-term goals, while investing aims to grow your wealth over time through calculated risk. Combining both strategies wisely helps you build financial security today while steadily moving toward long-term wealth.

    Savings vs Investing: 20 Best Trusted Examples to Build Wealth Safely


    Savings vs Investing Explained Simply

    Savings involve keeping money in low-risk instruments such as savings accounts or fixed deposits, where safety and easy access are priorities. Investing means putting money into assets like stocks, mutual funds, or bonds with the expectation of higher returns. Savings offer peace of mind, while investing helps beat inflation and grow wealth for long-term goals.


    Savings vs Investing Comparison

    The key differences between savings and investing lie in risk, return, and purpose. Savings offer low risk and predictable returns but limited growth potential. Investing carries higher risk but historically provides better returns over time. Savings are ideal for short-term goals, while investing is designed for long-term objectives like retirement, education, or wealth creation.


    Trusted Examples of Savings

    1 High-Yield Savings Accounts –

    High-yield savings accounts offer significantly higher interest rates than standard savings accounts while keeping your money accessible at any time. They are ideal for building an emergency fund or saving for short-term goals. With minimal risk and FDIC insurance (in many countries), these accounts provide safety and steady growth, making them a reliable choice for conservative savers.


    2 .Certificates of Deposit (CDs) –

    CDs are time-bound deposits that pay a fixed interest over a specific period, ranging from months to years. They are a low-risk way to earn better returns than a standard savings account. CDs are suitable for savers who do not need immediate access to funds, as early withdrawals often incur penalties, ensuring disciplined saving while preserving capital.


    3 .Money Market Accounts –

    Money market accounts combine moderate interest earnings with flexibility, often allowing check-writing and debit access. They are slightly higher-yielding than regular savings accounts but maintain low risk. Money market accounts are perfect for short-term goals, providing liquidity for emergencies while offering better returns than traditional savings, making them a practical choice for individuals and families seeking accessible growth.


    4 .Emergency Funds –

    An emergency fund is a dedicated savings reserve covering 3–6 months of living expenses. It protects against unexpected financial challenges, such as job loss, medical emergencies, or urgent home repairs. Keeping funds liquid in a high-yield account ensures immediate access without penalties, providing peace of mind. A strong emergency fund is the foundation of financial security before pursuing investments.


    5 .Fixed Deposits and Recurring Deposits

    – Fixed deposits (FDs) allow lump-sum deposits for a fixed tenure with guaranteed returns, while recurring deposits (RDs) enable regular monthly savings with interest. Both instruments are low-risk and help achieve specific short-term goals like vacations, weddings, or educational expenses. Their predictable growth, safety, and structured saving mechanism make them ideal for disciplined savers.


    6 .Senior Citizen Savings Schemes –

    Designed for retirees, senior citizen savings schemes offer secure, government-backed returns with attractive interest rates. They provide financial stability and predictable income during retirement, complementing pensions or other income sources. These schemes prioritize capital protection while ensuring steady growth, helping seniors maintain their lifestyle and meet healthcare or living expenses without risk of capital loss.


    7 .Business Contingency Funds –

    Business contingency funds are dedicated reserves set aside to manage unforeseen challenges such as sudden expenses, operational disruptions, or temporary revenue drops. These funds help small business owners maintain financial stability without compromising daily operations. Keeping money in liquid, low-risk accounts ensures immediate access, safeguarding the business from emergencies and reducing reliance on high-interest loans or credit lines.


    Trusted Examples of Investing

    1 . Stocks –

    Stocks represent ownership in companies, allowing investors to share in profits through dividends and potential capital appreciation. Investing in stocks can offer high returns over time, especially if you choose companies with strong growth potential. While stock prices fluctuate in the short term, a well-researched, diversified portfolio can help maximize long-term wealth accumulation.


    2 .Bonds –

    Bonds are fixed-income investments where you lend money to governments or corporations in exchange for regular interest payments. They are generally lower risk than stocks and can provide predictable income streams. Bonds are ideal for balancing a portfolio, preserving capital, and reducing volatility, making them an essential component of a diversified investment strategy.


    3 .Mutual Funds –

    Mutual funds pool money from multiple investors to invest in a diversified portfolio of stocks, bonds, or other securities. Managed by professional fund managers, they simplify investing for beginners and reduce risk through diversification. Mutual funds are suitable for those who want professional management and steady long-term growth without the need to pick individual securities.


    4 .ETFs (Exchange-Traded Funds) –

    ETFs are collections of assets like stocks or bonds that trade on stock exchanges like individual stocks. They combine diversification with flexibility, often tracking indices or sectors. ETFs usually have lower fees than mutual funds and allow investors to buy and sell throughout the day, making them ideal for both long-term growth and tactical investing.


    5 .Index Funds –

    Index funds are low-cost investment funds designed to replicate the performance of a specific market index, such as the S&P 500. They offer broad market exposure, low fees, and consistent long-term returns. For investors seeking a hands-off approach, index funds are a powerful way to participate in overall market growth while minimizing individual stock risk.


    6 .Real Estate –

    Real estate investing involves purchasing property to generate rental income or benefit from property appreciation. Physical real estate can provide steady cash flow, tax advantages, and portfolio diversification. While it requires more management and upfront capital than some investments, it is a tangible asset that often holds value even during market fluctuations.


    7 .REITs (Real Estate Investment Trusts) –

    REITs allow investors to access real estate markets without owning physical property. By pooling investor money to purchase income-generating properties, REITs provide liquidity, regular dividends, and potential for capital appreciation. They are an excellent option for those seeking exposure to real estate while maintaining flexibility and ease of investment.


    8 .SIPs (Systematic Investment Plans) –

    SIPs enable investors to make recurring, fixed-amount contributions to mutual funds. This methodical approach develops long-term financial habits, minimises market timing risk, and makes use of compounding. SIPs are very helpful for novice investors who want to gradually increase their wealth without requiring a sizable initial investment.


    9 .PPF (Public Provident Fund) & NPS (National Pension Scheme) –

    PPF and NPS are tax-advantaged long-term savings schemes designed to encourage retirement planning. PPF offers secure, government-backed returns, while NPS allows market-linked investments for higher growth potential. Both options help build a retirement corpus while providing financial discipline and tax benefits.


    10 .Gold Bonds and Precious Metals –

    Investing in gold bonds or other precious metals can safeguard wealth against inflation and currency fluctuations. They provide portfolio diversification and act as a hedge during economic uncertainty. Unlike physical gold, gold bonds offer fixed interest and ease of investment, making them a secure addition to a balanced portfolio.


    11 .Education Savings Accounts –

    These accounts are designed to save for children’s education costs. Contributions grow tax-free, and withdrawals for qualified educational expenses are usually exempt from taxes. Investing in such accounts ensures long-term financial planning for your child’s future and can significantly reduce reliance on loans or debt.


    12 .Annuities (Low-Risk Portion) – Annuities

    provide a guaranteed income stream over a fixed period or for life. They are ideal for conservative investors seeking long-term financial security, particularly during retirement. While returns may be lower than market-based investments, annuities reduce uncertainty and provide predictable cash flow, complementing riskier investments.


    13 .Robo-Advisors – Robo-advisors automate

    investment decisions using algorithms based on your risk profile and goals. They are low-cost, beginner-friendly, and offer portfolio diversification without the need for deep financial knowledge. Robo-advisors are excellent for hands-off investors who want professional guidance and automated portfolio management at minimal fees.


    14 .Sustainable/Ethical Investment Funds –

    These funds invest in companies that meet environmental, social, and governance (ESG) criteria. They allow investors to grow wealth while supporting responsible practices. Over time, ESG funds may outperform traditional investments due to better risk management and alignment with evolving market trends and consumer values.


    15 .Peer-to-Peer Lending Platforms (Low-Risk)

    – P2P lending connects borrowers with investors, providing regular interest income. Carefully selected low-risk P2P loans can diversify a portfolio and offer returns higher than traditional savings instruments. While some risk exists, thorough research, diversification, and using reputable platforms can make P2P lending a valuable alternative investment.


    When Should You Save vs Invest?

    Saving is ideal for goals under three years or money needed urgently. Investing is best for goals five, ten, or twenty years away, where short-term fluctuations matter less. A balanced approach—saving for security and investing for growth—ensures you are protected today while building wealth for the future.


    Common Mistakes People Make

    Many people keep all money in savings, which loses value over time due to inflation. Others invest without an emergency fund, forcing withdrawals during market downturns. Chasing high returns without understanding risk, ignoring diversification, or trying to time the market are also common pitfalls. Awareness of these mistakes can help you make smarter financial decisions.


    Savings vs Investing for Beginners

    Beginners should first build an emergency fund covering 3–6 months of expenses. Once secured, start investing gradually using simple, diversified options like index funds or SIPs. Learning basic risk management, staying consistent, and avoiding emotional decisions matters more than timing the market or chasing high returns. Patience and discipline are essential for long-term success.


    Is Savings Enough to Beat Inflation?

    Savings alone rarely beat inflation over time. While they protect capital, returns often fail to keep up with rising prices. Investing introduces growth potential that preserves purchasing power. A thoughtful mix of savings and investments is the most practical way to manage inflation and ensure your money grows sustainably

    Expert-Backed Rule for Balanced Finance

    Financial experts recommend dividing income between spending, saving, and investing strategically. Maintain an emergency fund, allocate money according to goal timelines, and diversify investments across asset classes to reduce risk. This structured approach balances short-term security with long-term growth, helping you achieve financial stability while steadily building wealth.


    Final Thoughts

    Savings and investing are not competitors—they complement each other in a healthy financial plan. Savings protect you from uncertainty, while investing drives wealth growth over time. By understanding when to save and when to invest, and by using trusted strategies, you can build financial security and confidently achieve long-term financial goals.


  • Beyond Finance Login: Step-by-Step Access Guide (2026 Updated)

    Beyond Finance Login: Step-by-Step Access Guide (2026 Updated)

    Accessing your Beyond Finance account is essential for managing your debt relief program, tracking progress, and communicating with support. The login portal gives clients a secure way to monitor payments, view settlements, and stay updated in real time. This guide explains the full login process, troubleshooting tips, and security practices to help you access your dashboard without any issues.

    Beyond Finance Login: Step-by-Step Access Guide (2026 Updated)

    2. What Is the Beyond Finance Client Portal?

    The Beyond Finance client portal is an online dashboard created for customers enrolled in the company’s debt relief program. It provides access to your payment schedule, settlement status, account balance, and support messages. The portal is designed for transparency, helping clients understand each step of the debt settlement process and stay fully informed throughout their financial journey.


    3. How to Login to Beyond Finance (Step-by-Step)

    To access your Beyond Finance account, start by visiting the official website and selecting the Client Login option. Enter the email address you used during registration and type your password. After this, complete the verification step if prompted. Once authenticated, you’ll be redirected to your dashboard, where you can check progress, view documents, and manage your payments.


    4. How to Reset Your Beyond Finance Password

    If you forget your password, simply click the “Forgot Password?” link on the login page. Enter your registered email, and you will receive a secure reset link. Follow the instructions to create a new password and regain access. For added protection, choose a strong password combining letters, numbers, and symbols to maintain account security.


    5. 5. Common Beyond Finance Login Issues”

    Some users face login problems due to incorrect credentials, outdated browsers, or temporary system glitches. Cached data, blocked cookies, or slow internet connections can also prevent successful login attempts. When errors occur, reviewing your email and password,updating your browser, or clearing cookies often helps restore access quickly and smoothly.


    6. Easy Fixes for Login Problems

    Begin troubleshooting by clearing your browser cache, refreshing the login page, or switching to a different device. If your password is incorrect, use the reset option to create a new one. Make sure your browser is updated and cookies are enabled. If none of these solutions work, contacting Beyond Finance support ensures faster resolution.


    7. Beyond Finance Mobile Login

    You can also access your account using any mobile browser. Just open the official website, tap the login option, and enter your credentials. The site is mobile-friendly, allowing you to check payments and messages easily. While Beyond Finance may not have a dedicated app for all platforms, the mobile login works efficiently on most smartphones.


    8. Beyond Finance Customer Support (For Login Help)

    If login issues continue, Beyond Finance’s customer support team is available to assist. They can verify your account, help reset access, or guide you through troubleshooting steps. Support is typically available through phone, email, and secure messaging. Response times are generally quick, especially for account-access problems that require immediate attention.


    9. Security Tips for Safe Login

    Always use a strong password and update it regularly to protect your account. Avoid logging in through public Wi-Fi, as unsecured networks can expose your information. Enable email notifications to monitor changes in your account. Logging out after each session also keeps your financial data safe and prevents unauthorized access.


    10. Conclusion

    The Beyond Finance login portal is an essential tool for managing your debt relief program and staying informed. By following the correct steps and using simple troubleshooting methods, you can easily access your dashboard anytime. Maintaining secure login habits ensures your information stays protected while you work toward long-term financial stability.


    15 FAQs About Beyond Finance Login

    1. What is the Beyond Finance Login portal?

    The Beyond Finance Login portal is a secure online dashboard that gives clients access to their debt relief account. It provides real-time updates on payment schedules, settlement progress, account documents, and communication from support. This portal helps users stay informed, monitor each step of the program, and maintain full visibility over their financial improvement journey.

    2. How do I access the Beyond Finance Login page?

    To access the Beyond Finance Login page, visit the official Beyond Finance website and click the “Client Login” option. Enter your registered email and password to sign in. The page works smoothly on mobile and desktop, making it easy to check your debt program status anywhere without needing special software or installing an app.

    3. Why is my Beyond Finance Login not working?

    When the Beyond Finance Login fails, it’s usually due to incorrect credentials, browser cache issues, outdated software, or unstable internet. Clearing cookies, refreshing your browser, or switching devices can help. If the problem continues, it may be a temporary server issue. Contacting customer support ensures quick troubleshooting and safe account recovery.

    4. How can I reset my Beyond Finance Login password?

    To reset your password, go to the Beyond Finance Login page and click “Forgot Password.” Enter your registered email to receive a secure link. Follow the instructions to set a new password. Choose a strong combination of characters for added security. This simple process restores access without compromising account protection or delaying your financial progress.

    5. Is the Beyond Finance Login portal secure?

    Yes, the Beyond Finance Login portal uses strong encryption, authentication steps, and secure data handling methods to protect your personal information. These security layers ensure your financial data remains private and inaccessible to unauthorized users. Following safe login habits, like avoiding public Wi-Fi and maintaining strong passwords, further enhances overall account protection.

    6. Can I use the Beyond Finance Login on my smartphone?

    Yes, you can access your account through the Beyond Finance Login on any mobile browser. The website is fully responsive and optimized for smartphones, allowing clients to check payments, settlement progress, and messages on the go. You don’t need a dedicated mobile app, as the portal is designed for smooth and secure mobile access.

    7. What should I do if I forget the email linked to my Beyond Finance Login?

    If you forget the email registered with your Beyond Finance Login, check any previous emails from Beyond Finance, as they usually indicate the account email. If you still can’t identify it, contact customer support. They’ll verify your identity and help you recover or update your login details, ensuring safe and uninterrupted access to your account.

    8. Does Beyond Finance have a mobile app for login?

    Currently, most users access their debt relief dashboard through the Beyond Finance Login on a mobile or desktop browser. Even without a dedicated mobile app, the portal is fully optimized for mobile. It loads quickly, displays clearly, and retains every function, making it easy to check program details anytime without additional downloads.

    9. Why is my Beyond Finance Login account locked?

    Your Beyond Finance Login account may be locked after multiple failed attempts or security triggers designed to protect your data. Waiting a few minutes before retrying usually helps. If the issue continues, use the password reset option or contact support. They’ll verify your identity and unlock your account securely, preventing unauthorized access.

    10. Can I update my personal details through the Beyond Finance Login portal?

    Yes, the Beyond Finance Login dashboard allows clients to update certain personal details like phone numbers, addresses, or communication preferences. Some changes—especially financial or legal details—may require support assistance for verification. Updating information regularly ensures you receive accurate notifications and helps the company negotiate settlements effectively on your behalf.

    11. What information can I see after logging in to Beyond Finance?

    Through the Beyond Finance Login, clients can view settlement progress, upcoming payments, completed negotiations, account balances, and important program documents. The dashboard also offers direct access to secure messages from the support team. This ensures total transparency and gives users a clear understanding of how their debt relief strategy is progressing over time.

    12. Can I make payments through the Beyond Finance Login portal?

    While payment deposits may be automated, the Beyond Finance Login portal allows you to view payment history and upcoming deposit schedules. Some users may have the option to update payment methods or adjust dates with support approval. This ensures that clients stay organized and aware of every transaction connected to their debt settlement program.

    13. What should I do if I see an error message on the Beyond Finance Login page?

    If you see an error message on the Beyond Finance Login page, refresh your browser and try again. Clear your cache, enable cookies, or switch to a different device for better results. Temporary server maintenance can also cause brief disruptions. If the error persists, contact customer support to review and resolve the issue efficiently.

    14. Can I contact customer support directly from the Beyond Finance Login dashboard?

    Yes, the Beyond Finance Login dashboard offers secure messaging features that let you communicate with the support team. You can ask questions, request updates, or report issues directly from your account. This built-in communication option makes it easy to receive timely assistance and ensures all messages remain securely stored within your profile.

    15. How often should I check my Beyond Finance Login account?

    It’s recommended to check your Beyond Finance Login account regularly to stay updated on new settlements, payment schedules, and important messages. Reviewing your dashboard weekly helps you monitor progress and confirm that deposits are running smoothly. Staying consistent ensures you remain fully informed and allows Beyond Finance to support you more effectively.

  • AI Tools for Finance and Accounting: Best 20 Solutions Today

    AI Tools for Finance and Accounting: Best 20 Solutions Today

    AI tools for finance and accounting are rapidly transforming how businesses manage transactions, reporting, forecasting, and compliance. By automating routine tasks and providing advanced insights, AI helps companies improve efficiency, reduce errors, and save valuable time. This evolution allows finance teams to focus more on strategy and less on manual administration, boosting overall financial performance.

    Today, AI adoption is accelerating across industries as organizations look for smarter ways to manage invoices, predict cash flow, detect fraud, and interpret complex financial patterns. With features like machine learning, generative AI, and robotic process automation, these tools offer accuracy and real-time intelligence. This blog highlights the best 20 AI solutions helping finance teams stay ahead in a competitive digital landscape.

    1. Why AI Matters in Finance and Accounting

    AI matters because it modernizes traditional finance processes that once required hours of manual effort. Tools powered by machine learning can classify transactions, extract data from invoices, and detect anomalies with greater precision. These capabilities dramatically reduce human error and improve compliance. AI-driven insights also support better decisions, especially in areas like budgeting, forecasting, and financial risk management.

    2. Categories of AI Tools in Finance

    AI tools can be grouped into several key categories to help businesses choose the most effective solutions. Bookkeeping and transaction automation tools reduce manual data entry and reconciliation tasks. Accounts payable and accounts receivable tools streamline invoice processing and payment cycles. FP&A tools strengthen planning and forecasting. Other categories support audit, compliance, analytics, market research, and contract accounting.

    3. Top 20 AI Tools for Finance and Accounting

    Below are the 20 best AI tools that provide real value for businesses, from startups to enterprises.

    1. QuickBooks Online Advanced (AI-Enhanced)

    QuickBooks uses intelligent automation to categorize transactions, reconcile accounts, and forecast cash flow. Its AI algorithms learn from your behavior to improve accuracy over time. This makes it ideal for small and medium businesses that need efficiency without complexity. The platform also includes smart dashboards that help owners monitor financial health quickly and clearly.

    2. Xero (AI Accounting Features)

    Xero applies AI to help identify transaction patterns, automate receipt capture, and speed up reconciliation. Its cloud-based structure helps teams collaborate easily and access data securely from anywhere. The system integrates with hundreds of business apps, making it reliable for faster data flow. Xero is especially helpful for growing businesses that need clear real-time financial visibility.

    3. Datarails

    Datarails provides automated data consolidation and analysis for FP&A teams. It collects information from CRMs, ERPs, spreadsheets, and financial systems, then uses AI to create accurate budgets and forecasts. This reduces manual spreadsheet tasks significantly. Finance teams save hours each month and gain better insights for decision making through real-time scenario planning and performance dashboards.

    4. Vena Solutions

    Vena combines Excel’s familiar environment with AI-driven insights, helping finance teams accelerate budgeting and reporting cycles. Its AI assistant provides quick analysis, predicts trends, and improves planning accuracy. This tool supports cross-function collaboration and reduces errors typically found in legacy spreadsheet processes. Vena is excellent for mid-size and enterprise organizations managing complex financial models.

    5. Vic.ai

    Vic.ai specializes in AP automation using advanced machine learning. It processes invoices without templates, learns from approval behavior, and makes decisions over time. The platform helps companies cut processing costs and reduce manual data entry. Finance teams benefit from increased efficiency, cleaner workflows, and faster month-end closing cycles.

    6. Docyt

    Docyt offers real-time bookkeeping with automated expense tracking and document extraction. It centralizes all receipts, bills, and statements into one organized system. Using AI, Docyt categorizes transactions and reconciles accounts continuously. This creates up-to-date financial reports businesses can rely on. It’s ideal for companies wanting automated financial visibility throughout the month.

    7. Trullion

    Trullion focuses on contract and lease accounting automation. AI reads data from contracts, extracts relevant details, and generates compliant reports under ASC 842 and IFRS 16. This reduces human error and audit risk. It also integrates with ERPs and accounting systems, making it useful for enterprises with complex lease portfolios.

    8. MindBridge AI

    MindBridge uses machine learning to identify risks and anomalies across financial data. It analyzes every transaction, spotting patterns auditors may overlook. This improves fraud detection and strengthens financial controls. Organizations benefit from greater audit accuracy and reduced risk exposure.

    9. Planful

    Planful Predict enhances FP&A operations with AI-powered forecasting, variance analysis, and automated insights. It helps finance teams transition from traditional budgeting cycles to continuous planning. AI identifies deviations early, supporting faster decision-making and improving financial agility. Planful is ideal for mid-to-large organizations.

    10. HighRadius

    HighRadius delivers AI-driven upgrades to accounts receivable, collections, and cash application. It predicts payment behavior, automates invoice matching, and enhances credit management. Companies improve cash flow visibility and reduce DSO. The platform is especially beneficial for enterprises with large receivable volumes.

    11. Zeni.ai

    Zeni combines AI and human expertise to offer full-service financial operations, including bookkeeping and real-time reporting. AI handles reconciliation and categorization while experts review accuracy. This hybrid model reduces workload and provides consistent financial insights for startup founders and executives.

    12. Kabbage (American Express)

    Kabbage uses AI to analyze cash-flow data and help businesses access working capital. It predicts financial needs and provides insights for smarter spending. This makes funding decisions faster and reduces reliance on manual financial reviews.

    13. Nanonets Flow

    Nanonets automates data extraction from invoices, receipts, and bank statements. The AI learns from previous inputs to improve accuracy, making it ideal for AP teams that handle large volumes. It integrates with ERPs, ensuring smooth end-to-end invoice workflows.

    14. Booke.ai

    Booke.ai acts as an AI assistant for accountants. It categorizes transactions, highlights missing data, and communicates with clients automatically. This tool helps accountants reduce repetitive tasks, deliver faster reports, and improve accuracy in client books.

    15. Truewind

    Truewind provides AI-powered bookkeeping blended with human review. It generates monthly reports, analyzes financial patterns, and provides insights for founders. Startups appreciate its simplicity, speed, and dashboard-style summaries.

    16. AlphaSense

    AlphaSense is an AI research engine that helps finance professionals analyze market data and economic insights. It scans billions of documents to deliver actionable intelligence. Investment teams use AlphaSense to make informed decisions quickly and confidently.

    17. Tableau (AI Analytics)

    Tableau offers smart AI-driven visualizations and predictive models. It helps finance teams transform raw data into clear insights. Natural language queries allow users to explore trends without technical skills. Tableau supports powerful financial storytelling and analysis.

    18. IBM Cognos Analytics

    Cognos automates data preparation and applies AI to forecasting and financial reporting. It helps enterprises build strong data-driven cultures and supports complex analytics. The platform integrates well with existing corporate systems.

    19. Alteryx

    Alteryx automates financial data cleaning, blending, and modeling. Its AI capabilities simplify complex calculations, making it ideal for FP&A teams needing advanced analytics. The platform reduces manual spreadsheet work and enhances forecasting precision.

    20. UiPath (RPA + AI)

    UiPath automates repetitive finance tasks by combining robotic process automation with AI. It handles invoice processing, compliance checks, and data migration. Companies use UiPath to reduce workloads, improve accuracy, and accelerate closing cycles.

    4. Key Considerations Before Choosing an AI Tool

    When selecting an AI tool, businesses should evaluate integration capabilities, data security, user training, and scalability. Ensuring the tool works seamlessly with existing ERPs or accounting systems is essential. Additionally, evaluate the transparency of AI decisions to support audit requirements. Cost, performance improvements, and long-term ROI also play a major role in selecting the right technology.

    5. Challenges of Using AI in Finance

    Despite its benefits, AI adoption comes with challenges. Data privacy concerns, regulatory requirements, and potential algorithm bias are common obstacles. Teams must maintain proper oversight to prevent reliance on inaccurate predictions. Implementation also requires time and resources to train staff. With proper management, these challenges can be minimized, allowing organizations to gain maximum value.

    6. Future Trends in AI for Finance

    The future of finance includes AI agents capable of handling end-to-end workflows, from processing transactions to preparing financial reports. Predictive analytics will become more accurate, helping companies manage risk better. Advanced AI-driven ERPs will unify accounting, planning, and compliance into a single intelligent system. Businesses adopting AI early will enjoy a competitive advantage.

    Conclusion

    AI tools for finance and accounting are no longer optional—they are essential for staying competitive. From automating invoices to predicting cash flow, these solutions save time, reduce errors, and provide intelligent insights. By choosing the right tools, businesses can modernize their financial operations and build stronger, more efficient workflows. Start small, test a few solutions, and gradually scale your AI strategy.

  • Automated Financial Systems: 20 Best Examples for Modern Business Success

    Automated Financial Systems: 20 Best Examples for Modern Business Success

    Automated financial systems are digital tools that streamline routine financial tasks by using AI, machine learning, and smart workflows. These systems reduce manual work and improve accuracy, helping businesses operate faster and more efficiently. As companies grow, automation ensures financial data remains organized, compliant, and transparent, making it easier to handle complex processes without increasing workload.

    2. Key Benefits of Automated Financial Systems

    The key benefits include improved accuracy, reduced human error, faster task execution, and significant cost savings. Automation also boosts compliance by following rules consistently and generating real-time financial reports. Businesses can scale confidently because automated systems handle larger workloads with ease, allowing teams to focus on strategy instead of manual data entry or repetitive tasks.

    3. How Automated Financial Systems Work

    These systems work by combining AI algorithms, rules-based workflows, and data integrations. They connect with accounting software, bank accounts, ERP systems, and payment platforms to automatically process financial information. Machine learning helps predict patterns like cash flow trends, while automation ensures tasks such as approvals, reconciliations, and reminders happen instantly without human intervention.

    4. Automated Billing & Invoicing Systems

    Automated billing systems create invoices, send payment reminders, track due dates, and update payment records instantly. They reduce the time spent on manual invoicing and ensure every customer receives accurate bills. These systems improve cash flow by accelerating the payment cycle and provide transparency through real-time tracking of invoices and customer payment status.

    5. Accounts Payable (AP) Automation

    AP automation tools scan invoices, extract data, match them with purchase orders, and route them for approval using a digital workflow. They eliminate paper-based processes and reduce fraud by ensuring every invoice is verified before payment. Automated AP also helps businesses avoid late fees and take advantage of early payment discounts through structured, timely processing.

    6. Accounts Receivable (AR) Automation

    AR automation helps businesses collect payments faster by sending automatic reminders, offering customer portals, and updating ledgers instantly. This system reduces the time spent chasing overdue invoices and improves customer payment experience. With real-time tracking, businesses can monitor aging reports and identify cash flow risks early, helping maintain stable financial health.

    7. Payroll Automation Systems

    Payroll automation calculates employee salaries, deductions, taxes, and benefits automatically every month. It ensures accuracy, compliance with tax laws, and timely salary disbursement. These systems reduce the chance of payroll errors that could impact employee trust. They also save hours of administrative work by eliminating manual calculations and repetitive data entry.

    8. Expense Management Automation

    Automated expense systems use AI to read receipts, categorize expenses, and match them with company policies. Employees can upload receipts from their phones, and the system processes them within seconds. This reduces manual review time and improves compliance with company spending rules. Managers gain instant visibility over who spends what, enabling smarter budgeting decisions.

    9. Automated Financial Reporting

    Financial reporting automation generates accurate balance sheets, profit-and-loss statements, and cash flow reports without manual preparation. These systems pull data directly from multiple sources, ensuring real-time insights. Automation reduces reporting errors, accelerates month-end closing, and helps leaders make strategic decisions based on reliable, up-to-date financial information instead of delayed manual reports.

    10. Bank Reconciliation Automation

    Bank reconciliation automation matches internal transaction records with bank statements automatically, saving hours of manual work. The system flags mismatches, duplicates, or suspicious entries for review. This ensures financial accuracy and reduces the risk of fraud or hidden discrepancies. With automated reconciliation, businesses maintain cleaner books and complete financial audits much faster.

    11. Tax Filing & Compliance Automation

    Tax automation tools calculate taxes, prepare filings, and generate compliance reports based on updated regulations. They help businesses avoid penalties by sending timely reminders for due dates and ensuring every calculation follows legal requirements. Automated compliance reduces the burden of manual paperwork and guarantees accuracy, especially for businesses handling multiple tax categories.

    12. Cash Flow Forecasting Automation

    Cash flow automation uses predictive analytics to forecast future inflows and outflows based on past data and current trends. These tools help businesses anticipate shortages, plan investments, and maintain stable cash reserves. Automated forecasting provides real-time visibility, making it easier to make financial decisions and adjust budgets according to expected market or operational changes.

    13. Procurement & Purchase Order Automation

    Automated procurement systems generate purchase orders, track approvals, and monitor vendor performance. They eliminate paper-based workflows and ensure spending stays within predefined budgets. Automation also reduces delays by ensuring every approval is routed instantly. Businesses gain full visibility into procurement activity, helping them negotiate better terms and reduce unnecessary purchases.

    14. Budgeting & Financial Planning Automation

    Budgeting automation uses AI to analyze financial data, create projections, and assist in building accurate budgets. The system updates figures in real time as new data enters, helping businesses respond quickly to changes. Automated planning reduces manual spreadsheet work and ensures planning accuracy, empowering teams to make strategic, data-driven financial decisions.

    15. Automated Investment Systems (Robo-Advisors)

    Robo-advisors manage investments using algorithms that select assets, balance portfolios, and respond to market movements. They offer personalized investment strategies based on risk level and financial goals. These automated systems reduce human bias, lower management costs, and make professional investment guidance accessible to businesses and individuals who want a hands-off approach.

    16. Fraud Detection & Risk Management Automation

    Fraud detection automation analyzes transactions in real time and alerts teams when unusual patterns occur. It uses machine learning to identify risks such as unauthorized access, duplicate payments, or suspicious vendor behavior. Automated systems strengthen financial security by detecting fraud early, reducing losses, and maintaining compliance with corporate governance standards.

    17. ERP-Based Automated Financial Systems

    ERP platforms like Oracle, SAP, and NetSuite automate entire financial workflows across departments. They integrate accounting, procurement, payroll, inventory, and reporting into a single system. Business leaders get real-time insights while reducing manual tasks. ERP-driven automation ensures consistency, improves decision-making, and supports rapid organizational growth through centralized financial management.

    18. POS & Payment Processing Automation

    Automated POS systems handle billing, payments, and receipts instantly while syncing all data to the accounting platform. They support recurring payments, refunds, and customer tracking. This automation reduces cashier errors and speeds up daily operations. Businesses gain accurate sales data, helping them make smarter decisions about pricing, inventory, and customer behavior.

    19. Automated Audit & Compliance Monitoring

    Automated audit systems continuously monitor financial data for compliance issues and policy violations. They identify anomalies, generate audit trails, and prepare reports instantly. This reduces the workload of traditional audits and ensures businesses stay compliant year-round. Continuous monitoring prevents costly mistakes and strengthens financial transparency.

    20. Choosing the Right Automated Financial Systems

    Choosing the right system depends on business size, workflow complexity, integration needs, and budget. Companies should evaluate scalability, user experience, AI capabilities, and support features. A good automated financial system should reduce manual labor, enhance accuracy, and align with long-term strategic goals. Investing wisely brings long-lasting efficiency and financial stability.

    21. Future Trends in Financial Automation

    Future trends include hyper-automation, predictive finance, AI-driven forecasting, and no-code automations. These advancements will allow businesses to automate even complex decision-making tasks. Integration between AI and finance will create smarter workflows, faster reporting, and stronger accuracy. The shift toward full digital transformation will make financial operations seamless, strategic, and fully data-driven.

    22. Conclusion

    Automated financial systems are transforming

  • Currency Adjustment Factor: 20 Best Ways to Calculate Accurately

    Currency Adjustment Factor: 20 Best Ways to Calculate Accurately

    Currency fluctuations can significantly impact pricing, contracts, and long-term financial planning. The Currency Adjustment Factor (CAF) is a structured method used to manage these fluctuations fairly and transparently.

    Businesses involved in international trade, logistics, and finance rely on CAF to reduce risk and maintain predictable costs. Understanding how to calculate CAF accurately helps ensure financial stability, compliance, and informed decision-making in volatile currency environments.


    Currency Adjustment Factor: 20 Best Ways to Calculate Accurately

    What Is Currency Adjustment Factor (CAF)?

    The Currency Adjustment Factor is a financial mechanism used to adjust prices or charges based on changes in currency exchange rates over time. It allows businesses to account for currency volatility without renegotiating contracts frequently. CAF is commonly applied in shipping, import-export agreements, and long-term service contracts where payments are affected by foreign exchange movements.


    Why Currency Adjustment Factor Is Important

    Currency Adjustment Factor plays a critical role in protecting businesses from unpredictable currency swings. It helps maintain fair pricing between parties, ensures cost recovery, and reduces the financial impact of sudden exchange rate changes. By using CAF, companies can plan budgets more accurately, avoid disputes, and improve trust with partners, especially in cross-border transactions where currency risks are unavoidable.


    How Currency Adjustment Factor Is Calculated

    CAF is calculated by comparing a base exchange rate with a current or reference exchange rate over a defined period. The difference between these rates determines the adjustment applied to prices or charges. Calculations may also include inflation data, cost structures, or currency indexes. Accurate inputs and transparent formulas are essential to ensure the adjustment remains fair and justifiable.


    20 Best Ways to Calculate Currency Adjustment Factor Accurately

    1. Historical Exchange Rate Method

    This method uses average exchange rates from a past period to determine adjustments. It smooths out short-term volatility and provides a stable reference point. Businesses often rely on this approach for long-term contracts where consistency is more important than reacting to daily market changes.


    2. Moving Average Method

    The moving average method calculates CAF using exchange rates averaged over rolling periods. This approach reduces the impact of sudden currency spikes and offers balanced adjustments. It is widely used in industries that prefer gradual cost changes rather than abrupt pricing shifts.


    3. Spot Rate Comparison

    Spot rate comparison uses current market exchange rates to calculate CAF. This method reflects real-time currency conditions and is suitable for short-term contracts. However, it may lead to frequent price changes if the currency market is highly volatile.


    4. Forward Exchange Rate Method

    This approach uses forward exchange rates agreed upon in advance. It provides predictability and reduces uncertainty. Businesses that want stable future pricing often prefer this method, especially when budgeting or forecasting international expenses.


    5. Inflation-Adjusted Method

    The inflation-adjusted method considers inflation differences between countries alongside exchange rates. This provides a more realistic view of purchasing power changes and helps maintain fairness in long-term financial agreements.


    6. Trade-Weighted Index Method

    This method uses a basket of currencies weighted according to trade volume. It reduces reliance on a single currency and offers a broader view of currency movements. It is commonly used by multinational businesses.


    7. Contract Base Currency Method

    CAF is calculated by fixing a base currency in the contract and adjusting prices based on deviations from it. This method simplifies calculations and reduces ambiguity between contracting parties.


    8. Central Bank Reference Rate Method

    This method uses official rates published by central banks. It enhances credibility and transparency, making it suitable for regulated industries and government-related contracts.


    9. Purchasing Power Parity (PPP) Method

    The PPP method aligns currency values based on purchasing power rather than market rates. It is useful for long-term comparisons but less effective for short-term pricing decisions.


    10. Cost-Based Adjustment Method

    This approach adjusts CAF based on changes in actual operating costs influenced by currency movements. It ensures adjustments reflect real financial impact rather than theoretical values.


    11. Hedging-Supported Calculation

    CAF calculations incorporate hedging instruments such as futures or options. This method provides additional protection against currency risk and is commonly used by large organizations.


    12. Risk Margin Inclusion Method

    A controlled risk margin is added to the CAF calculation to cover unexpected currency movements. This method balances risk management with fair pricing.


    13. Fixed Percentage Adjustment

    This simple method applies a fixed percentage adjustment regardless of market changes. While easy to apply, it should be reviewed regularly to avoid mispricing.


    14. Variable Threshold Method

    Adjustments are applied only when currency movements exceed a predefined threshold. This reduces frequent changes and simplifies administration.


    15. Index-Linked Adjustment Method

    CAF is linked to a recognized financial or currency index. This provides objectivity and consistency in adjustments over time.


    16. Multi-Currency Averaging

    This method averages multiple currency rates to reduce dependency on a single currency. It is effective for businesses operating across multiple markets.


    17. Market Volatility Method

    CAF is calculated based on volatility indicators, allowing adjustments to reflect market risk levels. This method is useful in highly unstable currency environments.


    18. Regulatory-Guided Method

    This approach follows industry or government regulations for CAF calculation. It ensures compliance and reduces legal risk.


    19. Automated Calculator Method

    Automated tools and calculators reduce manual errors and improve consistency. They are ideal for businesses that require frequent and accurate CAF updates.


    20. Expert-Reviewed Manual Method

    Calculations are manually prepared and reviewed by financial experts. This method ensures high accuracy and is often used for complex or high-value contracts.


    Common Mistakes to Avoid When Calculating CAF

    Common errors include using outdated exchange rates, ignoring inflation, and applying excessive adjustments without justification. These mistakes can lead to disputes, financial losses, and reduced trust between parties.


    Currency Adjustment Factor vs Exchange Rate

    An exchange rate reflects the current value between two currencies, while CAF is an adjustment mechanism applied over time. CAF provides stability and predictability, whereas exchange rates are more volatile and market-driven.


    Who Should Use Currency Adjustment Factor

    CAF is useful for importers, exporters, logistics companies, financial planners, and businesses involved in international contracts. It helps manage currency risk and maintain fair pricing structures.


    Best Practices for Safe CAF Application

    Always use reliable data sources, document calculation methods, and review CAF regularly. Transparency, consistency, and compliance with regulations are essential for maintaining trust and financial accuracy.


    Currency Adjustment Factor is a vital tool for managing currency risk in international finance. By using accurate calculation methods and following best practices, businesses can protect themselves from volatility, ensure fair pricing, and build long-term financial stability.

  • Real Estate Investment Analysis: 20 Best Trusted Tools

    Real Estate Investment Analysis: 20 Best Trusted Tools

    Real estate investing can be highly profitable, but only when decisions are backed by solid, data-driven analysis. Guesswork often leads to financial losses, missed opportunities, and poor investment performance. Modern investors rely on specialized tools to evaluate property performance, forecast profits, and assess risks before committing capital. Using the right analysis tools ensures better decision-making, increases confidence in investments, and ultimately improves the chances of building a successful real estate portfolio.

    Real Estate Investment Analysis: 20 Best Trusted Tools

    The Role of Technology in Modern Investing

    Technology has made property analysis faster, simpler, and more accurate than ever. Both beginners and experienced investors benefit from tools that automate complex calculations, track market trends, and provide real-time property insights. These tools save time, reduce errors, and allow investors to compare multiple properties efficiently. With the increasing availability of professional-grade software, even those new to real estate can now access the same analytical power as seasoned professionals.

    Understanding Real Estate Investment Analysis

    Real estate investment analysis is the process of evaluating a property’s potential for income and profit before purchasing it. This involves assessing cash flow, ROI, expenses, risk factors, and market trends. The goal is to make informed decisions that maximize returns while minimizing financial risk. Traditionally, investors relied on manual spreadsheets and personal experience, but today, software tools have transformed the process, providing faster, more accurate, and reliable insights for smarter property decisions.

    Why Investment Analysis Tools Are Essential

    Investment analysis tools are essential because they simplify complex calculations and provide clear reports on profitability and risk. Without tools, investors must manually evaluate data, which can be time-consuming and prone to errors. Tools allow for quick comparisons between properties, highlighting potential investment opportunities that meet specific financial goals. By leveraging these technologies, investors can save time, make better financial decisions, and reduce the risk of purchasing properties that may underperform or incur unexpected costs.

    Key Features of Reliable Tools

    A reliable investment analysis tool should include key features like ROI calculators, cash flow estimators, and detailed expense tracking. Additional features may include rental income forecasting, market trend analysis, and risk assessment reports. Some advanced tools provide portfolio management dashboards and scenario planning options, allowing investors to simulate different strategies. By selecting a tool with comprehensive features, investors can make data-driven decisions that maximize profitability and ensure a clear understanding of each property’s financial potential.

    Categories of Real Estate Investment Tools

    Real estate investment tools fall into several categories, each designed for specific needs. Financial analysis tools focus on cash flow, ROI, and profitability calculations. Market research tools provide insights into property trends, neighborhood demand, and pricing fluctuations.

    Valuation tools estimate fair market values, while rental income estimators help project monthly earnings. Portfolio management tools track multiple properties and evaluate overall performance. Using a combination of these tools gives investors a holistic view of their investments, improving strategic decisions.

    The 20 Best Trusted Tools for Investors

    Here is a list of the 20 best trusted real

    Estate investment analysis tools used by investors globally. These platforms have earned reputations for reliability, accuracy, and actionable insights. From beginner-friendly calculators to advanced AI-powered analytics, these tools cover all aspects of property evaluation, including cash flow, rental income, market research, and portfolio management. By exploring these tools, investors can select the most suitable platforms for their goals, budgets, and level of experience.

    Top Tools for Rental Analysis and ROI

    1. BiggerPockets Calculator – A simple yet powerful tool that helps investors calculate cash flow, ROI, and profitability for rental properties.

    2. Mashvisor – Provides predictive rental income analysis, property comparison, and market heatmaps to identify profitable locations.

    3. Roofstock – Offers turnkey rental property data, detailed performance metrics, and investment risk assessment for buyers.

    4. Zillow Investment Analysis – Tracks pricing trends, property valuations, and neighborhood growth potential to guide investment decisions.

    5. Realtor.com Market Tools – Provides property price history, market trends, and insights to help investors choose optimal locations.
    Tools for Professional Financial Modeling

    6. Property Evaluator Pro – Offers cash flow, tax, and expense calculations for both residential and commercial property investments.

    7. DealCheck – Quick property analysis tool suitable for beginners and professionals, offering detailed investment reports.

    8. PropStream – Advanced platform for market data, property analytics, and lead generation for real estate investors.

    9. Real Estate Financial Modeling (REFM) – Professional-level software for creating detailed investment models and financial projections.

    10. Redfin Data Center – Provides access to historical market data, pricing trends, and neighborhood analysis for investors.

    Commercial and Advanced Investment Tools

    11. RealData – Specialized tool for commercial real estate analysis and detailed investment projections.

    12. Excel Real Estate Templates – Spreadsheet-based solutions that allow customization for ROI and cash flow calculations.

    13. CoStar – Comprehensive commercial property database for market research, pricing trends, and property performance evaluation.

    14. LoopNet Insights – Offers analytics for commercial real estate, including trends, property listings, and investment performance.

    15. HouseCanary – AI-driven valuations, predictive analytics, and market forecasting for smarter property investment decisions.
    Tools for Lead Generation and Portfolio Management

    16. REIPro – Platform for lead generation, deal tracking, and investment management for both residential and commercial properties.

    17. PropertyShark – Provides property records, ownership information, and investment research tools for informed decision-making.

    18. Rentometer – Helps investors compare rental prices, estimate income potential, and evaluate rental demand.

    19. AirDNA – Analyzes short-term rental income, occupancy rates, and market trends for vacation rental investments.
    20. Stessa – Portfolio management platform that tracks income, expenses, and overall investment performance for multiple properties.

    Free vs Paid Tools for Investors

    Free tools are suitable for beginners who want to learn basic property analysis, evaluate ROI, and understand cash flow. They provide essential data without complex features, allowing novice investors to get started without significant upfront costs. Paid tools, on the other hand, offer advanced analytics, automation, and professional-grade insights. Serious investors often prefer paid solutions because they save time, reduce errors, and provide more precise market data to make smarter investment decisions.


    How to Choose the Right Tool

    Choosing the right investment analysis tool depends on your property type, investment strategy, and level of experience. Rental property investors should prioritize cash flow analysis and rental income forecasts. Commercial property investors benefit from advanced valuation and market demand tools. Budget and ease of use are also critical considerations. Beginners may start with free tools, while seasoned investors often invest in premium platforms that provide in-depth analysis, scenario planning, and portfolio management.

    Common Mistakes to Avoid

    Common mistakes investors make include relying solely on automated tool results without cross-checking real-world data. Ignoring hidden costs such as property maintenance, taxes, vacancy periods, and management fees can result in inaccurate calculations and poor decisions. Entering unrealistic or incomplete data further undermines reliability. To avoid these errors, combine professional tools with local market research, verify assumptions, and input accurate information to ensure investment projections reflect true potential profits and risks.

    The Future of Real Estate Tools

    AI and predictive analytics are shaping the future of real estate investment tools. Modern platforms can now forecast property values, simulate different investment scenarios, and detect emerging market opportunities.


    These innovations make investment planning faster, more accurate, and more reliable. Staying updated with evolving technologies gives investors a competitive advantage by providing better insights, improving decision-making, and ensuring that real estate portfolios are optimized for maximum long-term profitability.


    Conclusion: Start Using Trusted Tools Today

    Real estate investment analysis tools are essential for making informed, profitable, and low-risk property decisions. By automating calculations, tracking market trends, and providing actionable insights, these tools improve confidence and efficiency. Combining trusted tools with local research enables investors to identify better deals, avoid costly mistakes, and maximize long-term portfolio growth. Start leveraging these 20 trusted tools today to strengthen your investment strategy and achieve greater financial success in real estate.


    FAQS


    1. What is real estate investment analysis?
    Real Estate Investment Analysis is the structured method of examining a property’s income potential, expenses, risks, and appreciation prospects before buying. It helps investors determine whether a deal aligns with their financial objectives, time horizon, and tolerance for market uncertainty.

    2. Why is property analysis important before investing?
    Real Estate Investment Analysis is important because it reduces guesswork and emotional decision-making. By reviewing financial data and market indicators, investors can avoid overpaying, identify red flags early, and select properties that offer sustainable returns instead of short-term excitement

    .
    3. What financial metrics are commonly used in property evaluation?
    Real Estate Investment Analysis relies on metrics such as cash flow, net operating income, return on investment, capitalization rate, and internal rate of return. These indicators allow investors to objectively compare properties and measure expected profitability over the investment lifecycle.

    4. How does cash flow affect investment decisions?
    In Real Estate Investment Analysis, cash flow shows whether a property generates income after all expenses are paid. Positive cash flow supports financial stability, while negative cash flow increases risk and may require personal funds to sustain the investment long term.

    5. What role does location play in investment success?
    Location is a core element of Real Estate Investment Analysis because it influences rental demand, appreciation, and resale value. Properties in strong locations with jobs, infrastructure, and amenities generally outperform those in weaker or declining areas.

    6. How do market trends influence investment outcomes?
    Real Estate Investment Analysis considers market trends to assess pricing direction, rental growth, and demand. Studying trends helps investors avoid buying at market peaks and instead focus on areas with sustainable economic and population growth.

    7. What expenses should be considered when evaluating a property?
    Accurate Real Estate Investment Analysis includes mortgage costs, property taxes, insurance, maintenance, vacancies, management fees, and repairs. Ignoring even small recurring expenses can significantly reduce profitability and lead to unrealistic return expectations.

    8. How important is rental demand in decision-making?
    Rental demand is central to Real Estate Investment Analysis because it determines occupancy and income consistency. Strong demand lowers vacancy risk and stabilizes cash flow, while weak demand can lead to prolonged vacancies and reduced investment performance.

    9. What is the significance of property appreciation?
    Real Estate Investment Analysis evaluates appreciation as a long-term wealth-building factor. While appreciation is not guaranteed, it can significantly enhance returns when combined with solid cash flow and proper market selection.

    10. How does financing impact overall returns?
    Financing terms directly influence Real Estate Investment Analysis outcomes. Interest rates, loan tenure, and down payments affect cash flow and leverage, making financing strategy a critical factor in maximizing long-term investment returns.

    11. What risks should investors evaluate before buying?
    Real Estate Investment Analysis examines risks such as market downturns, vacancy rates, rising interest costs, regulatory changes, and unexpected repairs. Understanding these risks helps investors prepare reserves and avoid investments beyond their risk tolerance.

    12. How does property condition affect profitability?
    Property condition is assessed in Real Estate Investment Analysis because it impacts maintenance costs, tenant retention, and resale value. Poor condition may increase expenses and reduce returns, even if the purchase price appears attractive.

    13. What role does property management play in returns?
    Real Estate Investment Analysis accounts for property management efficiency, as good management reduces vacancies, controls expenses, and maintains tenant satisfaction. Poor management can quickly erode profits and create operational challenges.

    14. How can investors compare multiple properties effectively?
    Using consistent assumptions is essential in Real Estate Investment Analysis when comparing properties. Standardized metrics help investors objectively identify which property offers the best balance of risk, cash flow, and growth potential.

    15. Why is long-term planning essential in property investing?
    Real Estate Investment Analysis supports long-term planning by aligning property choices with future income needs, portfolio diversification, and exit strategies. Without planning, investors may experience unstable returns and missed growth opportunities.

    16. How do taxes affect property investment performance?
    Tax considerations are a key part of Real Estate Investment Analysis because property taxes, income taxes, and capital gains reduce net returns. Understanding tax impact helps investors structure deals more efficiently and preserve profits.

    17. What data sources are useful for evaluating properties?
    Reliable data strengthens Real Estate Investment Analysis by improving accuracy. Market reports, comparable sales, rental listings, and government statistics help investors make informed decisions rather than relying on assumptions.

    18. How often should an investor review property performance?
    Regular reviews are recommended in Real Estate Investment Analysis to ensure the property meets financial expectations. Periodic evaluations allow investors to adjust rents, refinance loans, or reduce expenses to improve performance.

    19. Can beginners successfully analyze property investments?
    Beginners can perform Real Estate Investment Analysis by learning core metrics, using basic tools, and starting with conservative assumptions. Education and professional guidance help reduce mistakes and build confidence over time.

    20. What is the biggest mistake investors make during evaluation?
    The biggest mistake in Real Estate Investment Analysis is overestimating income while underestimating expenses and risks. A conservative, data-driven approach leads to more realistic expectations and long-term investment success.


  • Whole of Life Insurance Calculator: 20 Best Trusted Plans to Secure Your Future

    Whole of Life Insurance Calculator: 20 Best Trusted Plans to Secure Your Future

    Planning long-term financial security for your family starts with choosing the right life insurance policy. Whole life insurance provides lifelong coverage, guaranteed benefits, and stable financial protection when planned correctly.
    Whole of Life Insurance Calculator tools make it easy to estimate premiums based on your age, coverage amount,

    and budget so you can start your insurance journey with clarity and confidence.
    Understanding policy costs before buying is essential to avoid overpaying or choosing insufficient coverage. With the right calculator, you can compare trusted insurance plans, evaluate benefits, and make well-informed financial decisions. This ensures your loved

    Whole of Life Insurance Calculator: 20 Best Trusted Plans to Secure Your Future

    What Is Whole of Life Insurance?

    Whole life insurance is a permanent life insurance policy that provides coverage for your entire lifetime as long as premiums are paid. Unlike term insurance, it does not expire after a set number of years. It also builds cash value over time, which you can borrow against or withdraw if needed, making it both protection and savings.

    What Is a Whole of Life Insurance Calculator?

    A Whole of Life Insurance Calculator is an online tool that estimates your insurance premium based on personal details. It considers your age, desired coverage amount, health status, and payment duration. This calculator gives an instant premium estimate, helping you understand affordability before contacting an insurance provider or purchasing a policy.


    Benefits of Using a Whole of Life Insurance Calculator

    Using a Whole of Life Insurance Calculator saves time and removes guesswork. It provides quick premium estimates, helps compare multiple plans, and improves financial planning. Instead of relying on agents alone, you can make informed decisions independently. This ensures transparency, prevents overpaying, and helps you select the most suitable lifetime protection plan.


    How to Use a Whole of Life Insurance Calculator (Step-by-Step)

    First, enter your current age and basic personal details. Next, choose the coverage amount you want your family to receive. Then select your premium payment duration or lifetime payment option. Finally, view the estimated premium instantly. This simple process allows you to adjust inputs and compare results easily before finalizing a policy.

    Key Factors That Affect Whole Life Insurance Premiums

    Several factors influence your whole life insurance premium. Age is the biggest factor — younger buyers pay lower rates. Health conditions and lifestyle habits such as smoking also affect cost. Higher coverage amounts increase premiums. Payment duration and policy features like riders further impact pricing, making calculators essential for accurate estimation.


    20 Best Trusted Whole Life Insurance Plans


    There are many reliable whole life insurance plans offered by top insurers worldwide. These plans provide guaranteed lifetime coverage, steady cash value growth, and flexible payment options. When using a Whole of Life Insurance Calculator, you can compare up to 20 trusted plan options side-by-side to find the best combination of affordability, benefits, and long-term financial security.


    Whole Life Insurance vs Term Life Insurance


    Whole life insurance offers permanent coverage and cash value benefits, while term life insurance provides protection only for a fixed period. Term plans are cheaper but expire after the term ends. Whole life policies cost more but never expire and accumulate savings. Your choice depends on long-term financial goals and family security needs.


    Who Should Buy Whole Life Insurance?

    Whole life insurance is ideal for individuals seeking lifelong protection, families planning estate security, and people wanting guaranteed savings growth. It is also useful for business owners handling succession planning. If you want both protection and financial stability in one product, whole life insurance is a strong long-term solution.


    Common Mistakes to Avoid

    Many people buy insufficient coverage, delaying purchase until premiums become expensive. Others ignore health disclosures or skip comparing plans. Not using a Whole of Life Insurance Calculator can lead to poor financial decisions. Avoid these mistakes by calculating premiums early, reviewing multiple policies, and choosing coverage based on future family needs.


    Final Thoughts

    A Whole of Life Insurance Calculator is a smart starting point for choosing the right lifetime protection plan. It helps you understand real costs, compare trusted insurers, and plan confidently. Whole life insurance is a long-term commitment, so using the right tools ensures your family remains financially secure for generations to come.


    FAQs – Whole of Life Insurance Calculator

    1. What is a Whole of Life Insurance Calculator?

    A Whole of Life Insurance Calculator is an online tool that estimates how much premium you may need to pay for a whole life policy. It uses details like age, coverage amount, and health status to give quick results. This helps users understand costs before speaking with an insurance provider.


    2. Is a Whole of Life Insurance Calculator free to use?

    Yes, most insurance websites and financial platforms offer a Whole of Life Insurance Calculator for free. You can enter your details and get instant premium estimates without registration or payment. This allows easy comparison of multiple plans before making a final decision.


    3. How accurate is a Whole of Life Insurance Calculator?

    A Whole of Life Insurance Calculator provides close premium estimates based on the information you enter. However, final premiums may change after medical examinations or insurer risk assessments. Still, it gives a reliable starting point for financial planning.

    4. What details are needed to use a Whole of Life Insurance Calculator?

    You typically need to enter your age, gender, desired coverage amount, health condition, and smoking status when using a Whole of Life Insurance Calculator. To increase estimate accuracy, some tools might also enquire about income and length of payment.


    5. Can I compare multiple plans with a Whole of Life Insurance Calculator?

    Yes, a Whole of Life Insurance Calculator allows you to compare estimated premiums across different insurers and coverage options. This helps you find the best balance between affordability, benefits, and long-term security before choosing a plan.


    6. Does using a Whole of Life Insurance Calculator affect my credit score?

    No, using a Whole of Life Insurance Calculator does not impact your credit score. It only provides premium estimates and does not perform any financial background checks. You can use it safely without worrying about credit records.

    7. Why do premiums differ in a Whole of Life Insurance Calculator?

    Premiums shown in a Whole of Life Insurance Calculator vary because insurers calculate risk differently. Age, health conditions, lifestyle habits, and coverage amounts influence results. This is why comparing multiple estimates is useful before buying a policy.

    8. Can I change coverage amount in a Whole of Life Insurance Calculator?

    Yes, a Whole of Life Insurance Calculator allows you to adjust coverage amounts freely. You can increase or decrease the sum assured to see how premiums change. This flexibility helps you choose coverage that fits your budget and family needs.

    9. Is medical information required in a Whole of Life Insurance Calculator?

    Most Whole of Life Insurance Calculator tools ask basic health questions such as smoking habits or pre-existing conditions. Detailed medical tests are not required at this stage. Final health verification happens only when applying for the policy

    .
    10. Can a Whole of Life Insurance Calculator help in financial planning?

    Yes, a Whole of Life Insurance Calculator helps in long-term financial planning by giving a clear idea of future insurance expenses. This allows better budgeting, prevents overcommitment, and ensures sustainable premium payments throughout life.

    11. Does a Whole of Life Insurance Calculator show cash value growth?

    Some advanced Whole of Life Insurance Calculator tools show estimated cash value accumulation over time. This helps users understand how their policy builds savings along with providing lifetime protection benefits.

    12. Can young people benefit from a Whole of Life Insurance Calculator?

    Yes, young individuals benefit from using a Whole of Life Insurance Calculator because premiums are lower at a younger age. Early planning ensures long-term savings, higher coverage affordability, and guaranteed lifetime protection.

    13. Do all insurers provide a Whole of Life Insurance Calculator?

    Most major insurance companies provide a Whole of Life Insurance Calculator on their websites. Financial comparison platforms also offer calculators that display multiple insurer estimates in one place for convenience.

    14. Is the premium shown in a Whole of Life Insurance Cal  final?

    No, the premium shown in a Whole of Life Insurance Cal  is an estimated value. Final premiums may change after medical tests, underwriting, and additional rider selections during policy purchase.

    15. Can I add riders using a Whole of Life Insurance Cal ?

    Some Whole of Life Insurance Cal  tools allow you to include riders such as critical illness or accidental death benefits. Adding riders increases premiums but enhances policy protection and coverage flexibility.

    16. How often should I use a Whole of Life Insurance Cal ?

    You should use a Whole of Life Insurance Cal whenever your financial situation changes. Marriage, children, income growth, or new responsibilities may require higher coverage and updated premium planning.

    17. Is a Whole of Life Insurance Cal suitable for senior citizens?
    Yes, a Whole of Life Insurance Calculator can help senior citizens estimate coverage costs. However, premiums may be higher due to age, so using a calculator helps assess affordability before purchasing a policy.

    18. Can I buy a policy directly after using a Whole of Life Insurance Cal ?

    Yes, many platforms allow you to proceed with policy purchase after using a Whole of Life Insurance Cal . However, it is recommended to review policy terms carefully before finalizing the application.

    19. Why should I trust results from a Whole of Life Insurance Cal ?

    A Whole of Life Insurance Cal  uses insurer-approved pricing models to generate estimates. While not final, these results provide a realistic idea of costs and help you make better-informed insurance decisions.

    20. What is the biggest benefit of a Whole of Life Insurance Cal ?

    The biggest benefit of a Whole of Life Insurance Cal is clarity. It removes confusion about premiums, supports easy plan comparison, and helps you choose a trusted lifetime protection plan with confidence and financial awareness.